

Mid-Week Market Highlights: AI Chips, Oil, and Fed Focus
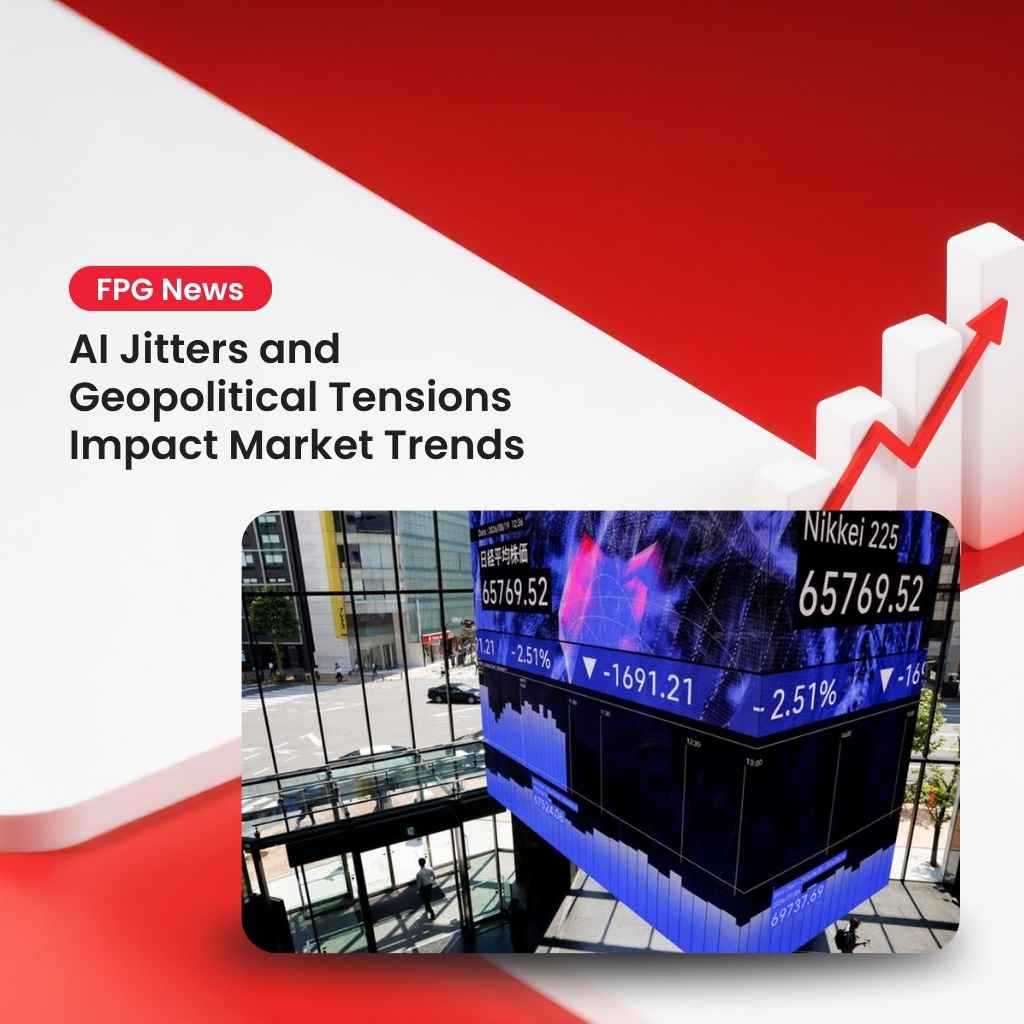
Global markets displayed mixed performance in the mid-week session on July 29, 2026, as an AI chip selloff rattled equity indices while crude oil rebounded and attention turned to major technology earnings and the Federal Reserve policy decision. Concerns over elevated AI infrastructure spending and advancing chip capabilities in China contributed to sharp declines in semiconductor-related stocks. Asian benchmarks stabilised after earlier losses, with South Korea’s KOSPI previously plunging as much as 8.1 percent and Japan’s Nikkei falling 4 percent. U.S. Nasdaq 100 futures approached technical correction levels amid the broader risk-off tone.
Market participants monitored these developments closely as Fortune Prime Global continued providing clients with access to diverse trading opportunities across equities, commodities and currencies. The mid-week session highlighted divergences across asset classes, from technology weakness to gains in certain consumer and healthcare names.
Key Takeaways:
- AI chip selloff leads to significant declines in semiconductor stocks, affecting global equity indices.
- Crude oil rebounds by 4.30% amid supply concerns, contrasting with the tech sector’s weakness.
- Asian markets stabilize after a sharp selloff, with Japan’s Nikkei and South Korea’s KOSPI showing recovery signs.
- Cryptocurrencies face headwinds from a stronger dollar and tech selloff, with Bitcoin nearing a 10-day low.
- Federal Reserve’s policy decision looms large, impacting market sentiment and keeping the dollar firm.
Asian Equities Stabilise After Earlier Rout
Asian stocks rebounded on Wednesday following a brutal selloff the previous day. Anxiety about valuations, rising competition and heavy AI-related spending had rocked regional markets. The recovery occurred ahead of crucial earnings from large technology firms and the upcoming Federal Reserve policy announcement.

Japan’s Nikkei and South Korea’s KOSPI showed signs of stabilisation after the prior session’s steep drops. Broader regional sentiment improved as investors assessed the extent of the technical correction in semiconductor-heavy indices. The move reflected a pause in selling pressure rather than a decisive shift in underlying fundamentals.
Semiconductor and Memory Chip Pressure Persists
The AI chip selloff extended to memory manufacturers despite some strong earnings reports. SK Hynix posted a 557 percent surge in quarterly operating profit driven by booming AI chip demand. The company still missed forecasts, underscoring elevated expectations in the sector.
SanDisk declined 9 percent, Micron dropped 7 percent and Western Digital fell 8 percent. Investors questioned the sustainability of memory pricing amid concerns over massive infrastructure spending. These moves contributed to broader weakness in technology shares, with the sector down approximately 1.84 percent in recent trading.

Individual names showed mixed results within the technology space. Some semiconductor stocks posted modest gains while others, including certain memory and equipment makers, recorded steeper losses. The pattern illustrated selective pressure rather than uniform declines across the industry.
Crude Oil Rebounds on Supply Concerns
Crude oil surged 4.30 percent to $82.67 after a three-day decline. The rebound followed a pause in U.S.-Iran hostilities and renewed Middle East tensions. Disruptions near the Strait of Hormuz and Red Sea shipping routes reignited supply concerns.
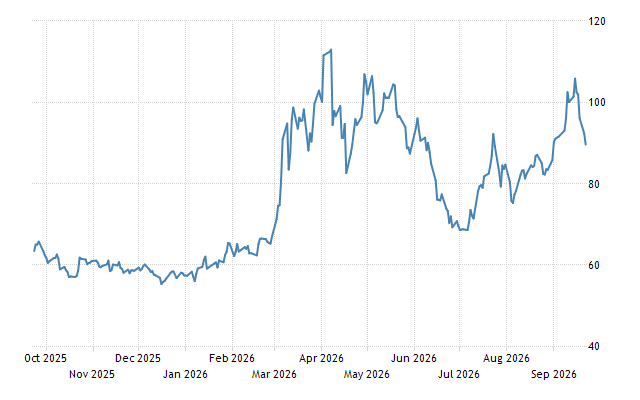
China continued securing Middle East oil supplies despite the regional turmoil. Light crude oil futures traded near $82.60, marking a 4.21 percent advance. Natural gas also posted gains of around 1.39 percent. The energy complex showed resilience even as equity markets faced pressure from technology and risk assets.
Cryptocurrencies and Risk Assets Face Headwinds
Bitcoin slipped toward a 10-day low, trading near $63,807.95. The move reflected the broader technology and AI-linked selloff combined with uncertainty ahead of the Federal Reserve’s rate decision. Risk assets came under pressure as the dollar strengthened.

Gold eased as war fears diminished and the dollar gained ground. Bitcoin later recovered modestly to around $63,797, posting a 0.98 percent gain in some sessions. Ethereum advanced 1.66 percent to approximately $1,912, while other major cryptocurrencies including Solana and XRP also recorded positive daily changes. The crypto market heatmap indicated predominantly green performance across larger capitalisations despite earlier weakness.
Federal Reserve Policy Decision Looms Large
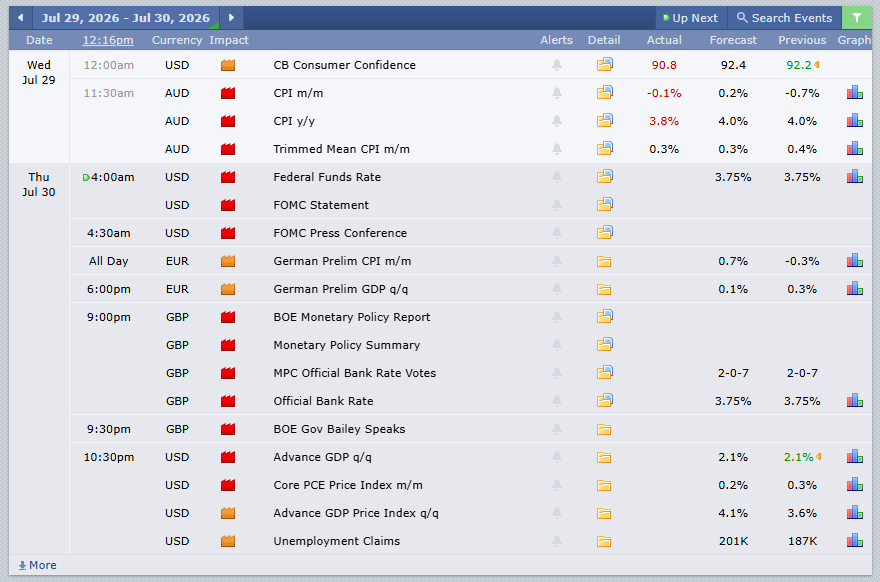
Bank of America described a potential July rate hike as unprecedented. The bank expected the Federal Reserve to hold rates, though with possible hawkish dissents. Markets had priced in roughly 10 basis points of tightening risk.
Rate futures indicated a 79.4 percent chance of a 25 basis point hike by the September FOMC meeting. The outlook kept the dollar firm. U.S. equity futures showed divergence, with S&P 500 futures up 0.42 percent, Dow futures advancing 1.14 percent and Nasdaq futures declining 0.75 percent. The VIX fell 2.46 percent to 18.21, signalling a modest reduction in near-term volatility expectations.
Big Tech Earnings Draw Investor Attention
Microsoft and Meta prepared to report results on July 29. Both companies entered the period with high beat odds already reflected in valuations near 95 percent. Investor focus shifted toward fiscal year 2027 capital expenditure guidance.
Microsoft’s cloud and AI run-rate growth remained strong. Meta’s advertising-driven revenue jumped 33 percent, though its Reality Labs unit continued to post steep losses. The reports carried significance for broader technology sentiment after the recent semiconductor pressure.
Equity Sector Divergences and Corporate Updates
Equity sectors displayed clear divergences. Technology declined 1.84 percent while energy fell 1.35 percent. Consumer cyclical shares rose 1.48 percent and consumer defensive names gained 1.99 percent. Communication services advanced 1.87 percent, healthcare climbed 2.37 percent and financial services increased 1.27 percent.
Corporate announcements contributed to the mixed picture. Coca-Cola raised its outlook after a 5 percent jump in case volume fuelled by World Cup advertising. Ford lifted guidance on expectations of higher U.S. vehicle pricing. In contrast, Mercedes-Benz cut sales guidance as Chinese car sales plunged 30 percent, weighing on its global outlook.
Clean energy stocks slid ahead of earnings. Bloom Energy fell 13 percent, FuelCell dropped 7 percent and Plug Power declined 4 percent. The moves reflected wider caution toward speculative energy transition names amid the prevailing risk-off tone.
Currency Markets and Commodity Backdrop
Currency pairs showed varied performance across major crosses. The euro traded near 1.13893 against the U.S. dollar. The Australian dollar stood at approximately 0.69521 versus the greenback. Other pairs, including sterling, the New Zealand dollar, Canadian dollar, Swiss franc, Japanese yen and Chinese yuan, reflected relative strength or weakness depending on the base currency.
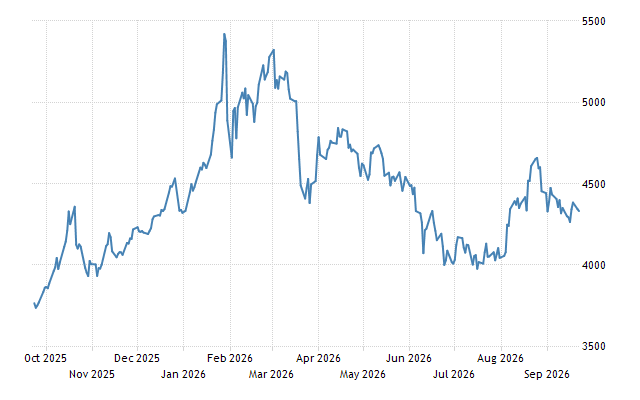
Gold traded near $4,017 per ounce, down 0.54 percent. Silver, copper and platinum also recorded declines. The broader commodity complex remained influenced by the oil rebound and shifts in risk sentiment.
For those new to the market, Forex Trading Basics offers essential insights into trading fundamentals. Understanding currency movements and their relationship to equity and commodity trends forms a core component of market analysis.
Neutral Close to the Mid-Week Session
The mid-week session on July 29, 2026, captured a market balancing semiconductor and technology pressure against stabilisation in Asian equities, a firm rebound in crude oil and anticipation of major corporate earnings and the Federal Reserve decision. Sector performance varied widely, with consumer, healthcare and certain communication names outperforming while technology and clean energy lagged. Cryptocurrencies recovered some ground after earlier weakness, and volatility measures eased modestly.
Fortune Prime Global remains focused on delivering transparent market access for clients navigating these conditions. Overall trading activity reflected ongoing assessment of AI-related valuations, geopolitical supply factors and monetary policy expectations without a single dominant directional bias across all asset classes.
People Also Ask:
What caused the AI chip selloff?
The AI chip selloff was driven by concerns over elevated infrastructure spending and advancing chip capabilities in China, leading to sharp declines in semiconductor-related stocks.
Why did crude oil prices rebound?
Crude oil prices rebounded due to supply concerns stemming from U.S.-Iran hostilities and renewed Middle East tensions affecting shipping routes.
How did Asian markets react to the selloff?
Asian markets, including Japan’s Nikkei and South Korea’s KOSPI, showed signs of stabilization after an initial sharp selloff, reflecting a pause in selling pressure.
What is the focus of the Federal Reserve’s policy decision?
The Federal Reserve’s policy decision is focused on potential rate hikes, with markets pricing in a chance of a 25 basis point increase by the September FOMC meeting.
How are cryptocurrencies performing amid market fluctuations?
Cryptocurrencies faced headwinds from a stronger dollar and tech selloff, but some like Ethereum showed modest gains despite broader market pressures.