

Japanese Yen Depreciation Persists Amid Structural Pressures and Policy Divergence
The Japanese Yen has weakened to near 40-year lows against the US Dollar, trading in the 161 to 162.6 range in mid-July 2026. This depreciation reflects ongoing macroeconomic imbalances, including wide interest rate differentials with the United States and Japan’s reliance on imported energy.
According to data from the Federal Reserve and market sources, the USD/JPY pair reached levels around 162.6 in late June before moderating slightly. The trend highlights deep structural challenges for the Japanese economy despite recent policy adjustments by the Bank of Japan (BOJ).
Key Takeaways:
- The Japanese Yen has weakened to near 40-year lows against the US Dollar, trading in the 161 to 162.6 range in mid-July 2026.
- Interest rate differentials between Japan and the US, driven by the BOJ’s gradual tightening and the Federal Reserve’s higher rates, continue to drive capital outflows and depreciation.
- Japan’s reliance on imported energy and commodities, combined with elevated global energy prices, have widened trade deficits and added downward pressure on the currency.
- The BOJ’s gradualism in monetary policy has contributed to market perceptions of limited further tightening, sustaining capital outflows and depreciation.
- The weak Yen contributes to imported inflation, raising costs for food and energy, while supporting a tourism boom and enhancing competitiveness for Japanese exporters.
Interest Rate Differentials Drive Carry Trade Activity
A primary factor behind the Japanese Yen depreciation remains the persistent gap between Japanese and US monetary policy rates. The BOJ raised its policy rate to 1.0 percent on June 16, 2026, in a 7-1 vote, marking the highest level since the mid-1990s. However, this remains well below US Federal Reserve rates, currently around 3.5 to 3.75 percent.
This differential encourages the Yen carry trade, where investors borrow in Yen at low costs to invest in higher-yielding US assets. Market participants continue to price in limited further tightening from the BOJ compared to potential US policy firmness, sustaining capital outflows.
Fiscal Constraints Limit BOJ Aggressiveness
Japan’s substantial public debt restricts the BOJ’s room for rapid rate hikes. Significant increases in borrowing costs could strain government finances, leading policymakers to balance debt servicing needs with currency stability priorities. This dynamic has contributed to market perceptions of gradualism in Japanese monetary policy.
Trade Deficits and Energy Import Pressures
As a resource-scarce nation, Japan depends heavily on imported fossil fuels and commodities. Elevated global energy prices, influenced by geopolitical tensions in the Middle East, have prompted Japanese firms to sell Yen for foreign currencies, widening trade deficits and adding downward pressure on the currency.
Cost-push inflation has emerged from these import costs rather than strong domestic demand, further complicating the economic picture.
Capital Outflows and Market Sentiment
Japanese institutions and investors have maintained capital abroad seeking better returns. Speculative positioning on sustained US Dollar strength has reduced the impact of past interventions by the Ministry of Finance. Authorities spent a record amount earlier in 2026 to support the Yen, yet the currency has remained vulnerable.
Monetary Policy Evolution and Historical Context
For years, the BOJ maintained ultra-loose policy, including negative interest rates and yield curve control, diverging from global tightening trends post-COVID. The central bank has since exited negative rates and implemented gradual hikes, reaching 1.0 percent in June 2026. Markets, however, view the pace as insufficient relative to international yields.
The next BOJ meeting is scheduled for July 30-31, 2026, with expectations of measured further adjustments.
GDP and Inflation Trends
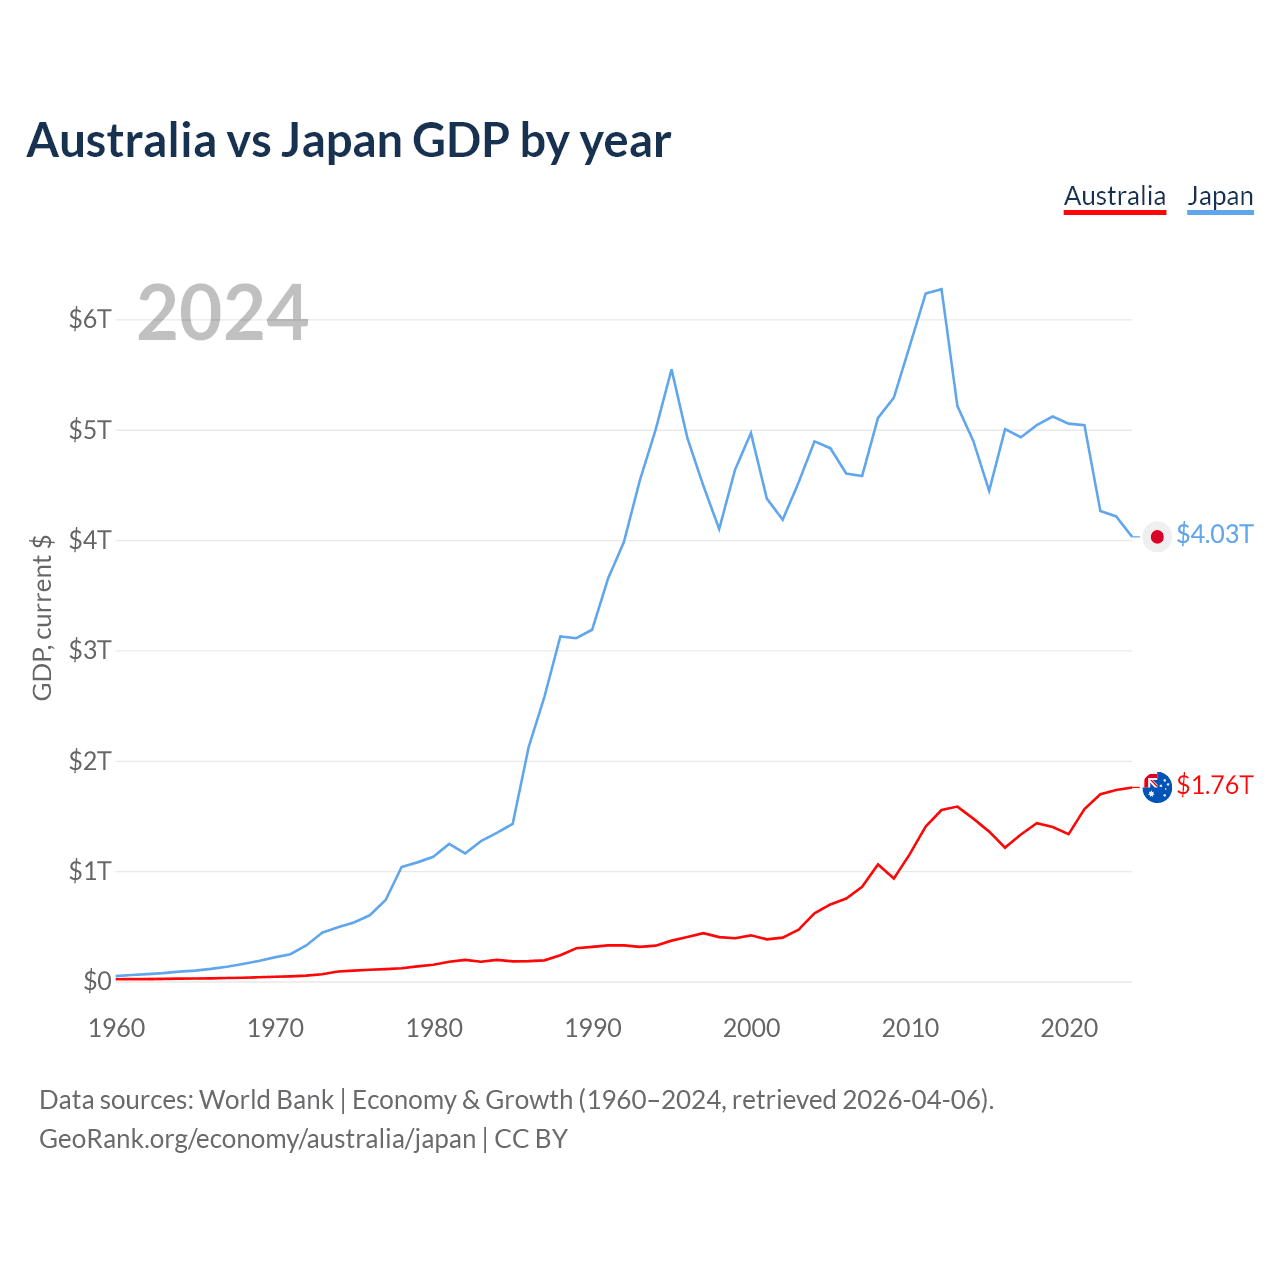
Japan’s GDP growth forecasts remain modest, with projections around 0.5 to 1.3 percent for fiscal 2026 depending on sources. Real wages face pressure despite nominal gains, as cost-push inflation from imports affects household budgets.
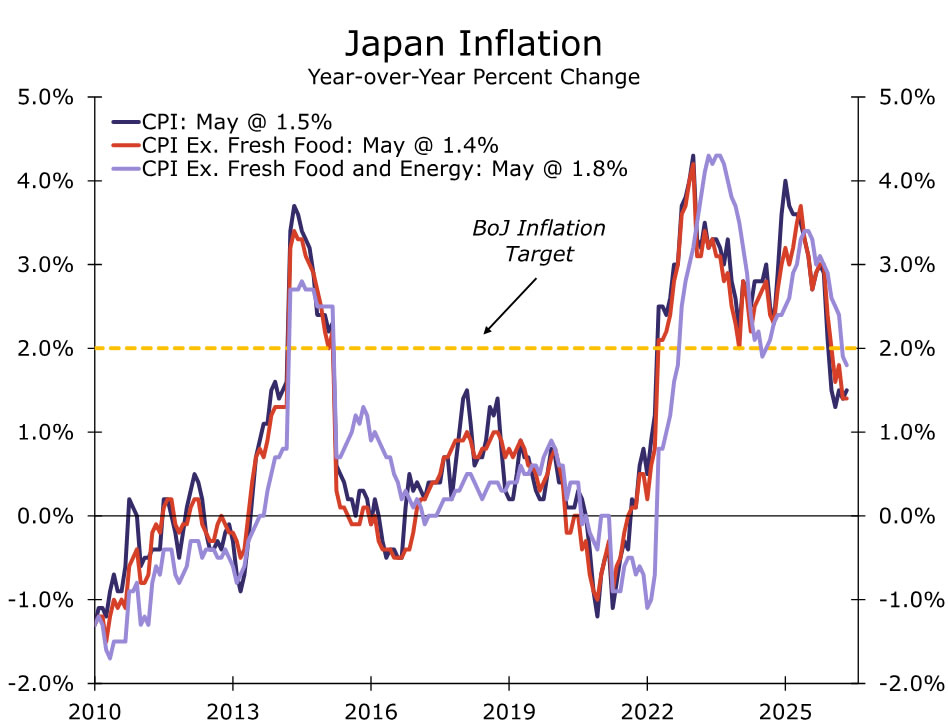
Underlying inflation dynamics show persistence, driven largely by external factors. The BOJ continues to monitor risks of inflation exceeding its 2 percent target over the medium term.
Geopolitical and External Influences
Ongoing volatility in global oil and commodity markets, linked to Middle East developments, exacerbates challenges for Japan. Higher import costs reinforce the need for foreign currency, creating a feedback loop that weakens the Yen and raises expenses for subsequent imports.
Short-Term Economic Implications
In the near term, the weak Yen contributes to imported inflation, raising costs for food and energy and straining household budgets. Conversely, it supports a tourism boom as foreign visitors benefit from stronger purchasing power and enhances competitiveness for Japanese exporters.
Medium-Term Considerations for the Japanese Economy
Over a longer horizon, sustained depreciation may suppress domestic consumption through falling real wages. It could also encourage shifts in supply chains toward foreign manufacturing amid fluctuating production costs.
Global Market Spillovers
The Japanese Yen depreciation influences broader markets through carry trade volatility and potential unwinding events. Japanese exporters gain advantages, but Asian trade partners face competition from cheaper Japanese goods. Repatriation of capital could affect foreign bond markets.
Intervention Signals and Policy Outlook
Japanese authorities have reiterated readiness for “appropriate action” to address excessive volatility. Past interventions provide context, though fiscal priorities emphasize growth and reflation. Thresholds for major moves appear elevated, with some analysis pointing toward higher levels before significant steps.
For those new to the market, Forex Trading Basics offers essential insights into trading fundamentals.
FPG Fortune Prime Global, a reputable Forex Broker, benefits its clients with access to competitive conditions in global currency markets via its platform at https://fortuneprime.com/.
Summary of Developments
The Japanese Yen depreciation to multi-decade lows underscores the interplay of interest rate differentials, fiscal limitations, energy dependencies, and capital flows. While supporting certain sectors like exports and tourism, it poses challenges for households and import costs. The BOJ’s gradual tightening continues, with markets watching upcoming decisions closely. This situation reflects broader structural shifts in Japan’s economy amid global uncertainties.
People Also Ask:
- What are the main drivers of the Japanese Yen depreciation?
The main drivers are interest rate differentials, fiscal limitations, energy dependencies, and capital flows.
- How has the BOJ’s monetary policy contributed to the depreciation?
The BOJ’s gradualism in monetary policy has contributed to market perceptions of limited further tightening, sustaining capital outflows and depreciation.
- What are the implications of the weak Yen on the Japanese economy?
The weak Yen contributes to imported inflation, raising costs for food and energy, while supporting a tourism boom and enhancing competitiveness for Japanese exporters.
- What are the potential risks and challenges associated with the Japanese Yen depreciation?
The potential risks and challenges include imported inflation, trade deficits, and economic instability.
- What is the current outlook for the Japanese Yen?
The current outlook is uncertain, with potential for further depreciation or stabilization depending on future economic developments and monetary policy decisions.