


Weekly Market Watch: Bitcoin Surge, Equity Pressures and Commodity Moves Shape Trading Week
Global financial markets delivered a mixed performance over the five trading days ending August 20, 2026. Bitcoin Surge sharply toward the $74,000 level while major equity indices faced selective pressure from corporate results and geopolitical headlines. The dollar index fluctuated before stabilizing, crude oil held firm near recent ranges, and gold recovered ground on softer labor data. Forex pairs showed limited directional conviction as traders digested Treasury actions and Federal Reserve signals.

These developments formed the core of this week’s Market Watch. Liquidity conditions, policy cues and sector-specific news drove the primary moves across asset classes.
Key Takeaways:
- Bitcoin surged sharply, reaching near $74,000, driven by Treasury buybacks and ETF demand.
- Equity markets experienced mixed performance, with Walmart and other consumer stocks under pressure.
- Crude oil remained steady near $90 per barrel, supported by geopolitical commentary from President Trump.
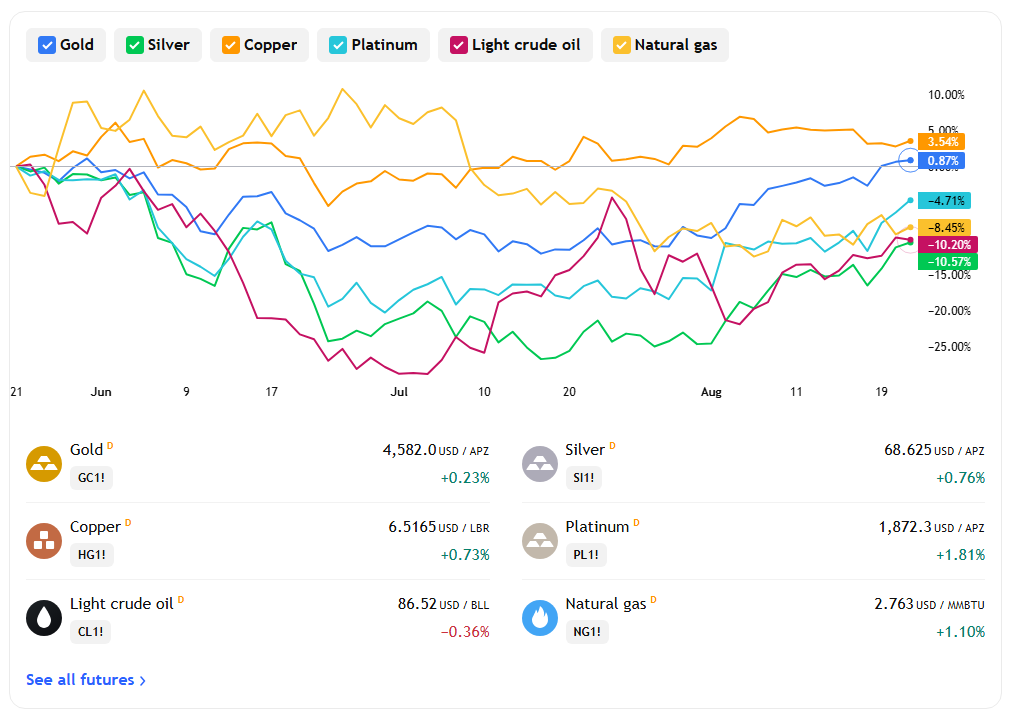
- Gold recovered on softer labor data and strong manufacturing figures, rebounding to around $4,470-$4,582 per ounce.
- Dollar index stabilized after initial softness, following the Treasury’s expanded buyback announcement.
Bitcoin Surge on Treasury Buybacks and ETF Demand
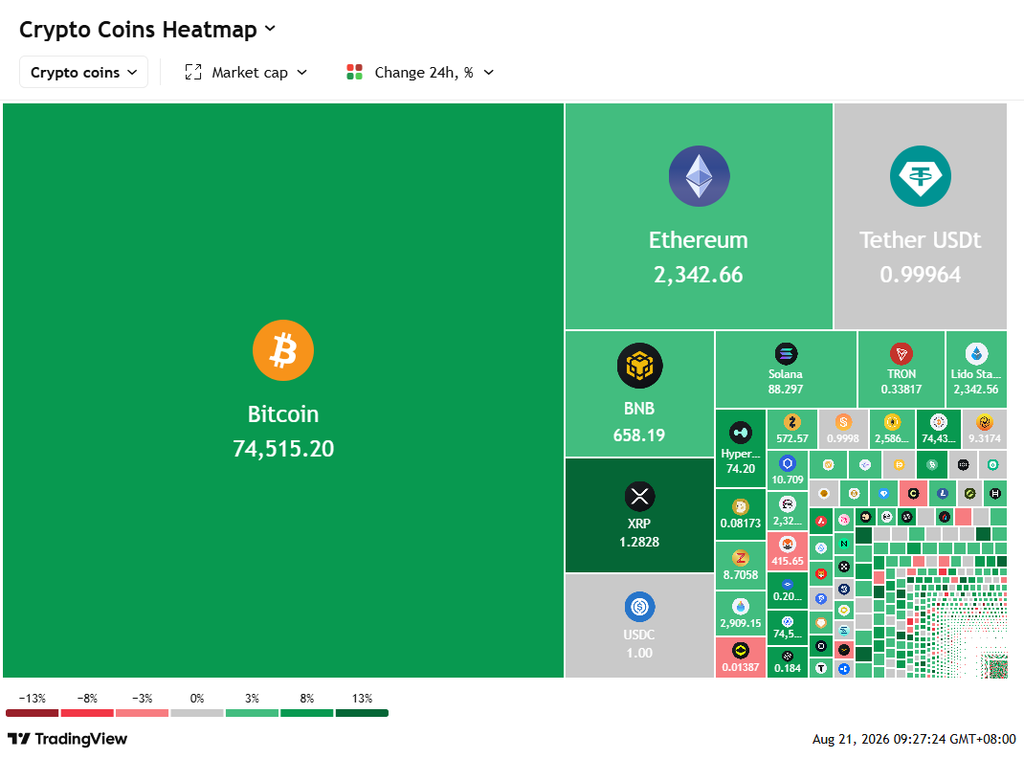
Bitcoin rose from the low $60,000s to approximately $74,000 during the period. The advance reflected roughly a 7 percent gain on certain readings. The U.S. Treasury increased long-dated bond buyback operations to $4 billion. This step eased upward pressure on yields and contributed to a softer dollar backdrop.
Spot Bitcoin exchange-traded funds recorded strong daily inflows. Dovish language in the Federal Reserve’s July FOMC minutes added further support. Ethereum and several other altcoins posted double-digit percentage gains in the same window. Crypto market heatmaps at the close of the week showed Bitcoin trading near $74,515 with broad green across major tokens.
The combination of official sector demand and reduced yield competition helped sustain the move through the later sessions of the week.
Dollar Index Stabilizes After Initial Softness
The U.S. dollar index declined to a more-than-three-month low near 98.77 before recovering 0.1 percent to approximately 98.90. The rebound followed the initial market reaction to the Treasury’s expanded buyback announcement. EUR/USD held near the 1.17 area as participants balanced the Treasury’s yield-management efforts against lingering inflation concerns.
Cross rates remained relatively contained. Major pairs such as GBP/USD, AUD/USD and USD/JPY showed only modest daily ranges. The overall tone in the currency market stayed cautious rather than directional.
Equity Markets Face Mixed Corporate and Sector Pressure
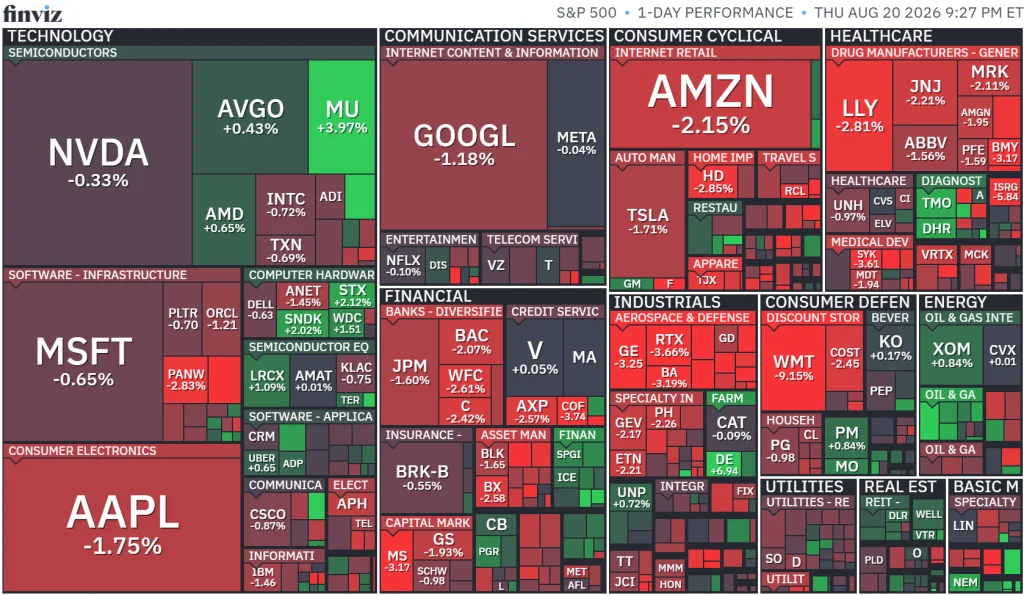
U.S. equity performance diverged sharply by sector. The S&P 500 one-day heatmap on August 20 highlighted widespread weakness in consumer-related names. Walmart shares declined after the company reported its slowest sales growth in more than six years. The print raised questions about consumer spending resilience and contributed to broader softness in retail-linked equities.
Walmart registered a decline of roughly 9 percent on the day in the heatmap. Other consumer cyclical and healthcare names also finished lower. Technology leaders such as Nvidia, Microsoft and Apple posted modest declines. Selected semiconductor names including Micron advanced.
Moderna shares moved higher by approximately 24 percent after reports of a cancer vaccine development. The stock became one of the stronger performers in the S&P 500 year to date. Retail message volume on related platforms rose sharply.
Nebius Group shares fell 3 to 10 percent following the pricing of an upsized convertible note offering intended to fund AI cloud expansion. SpaceX shares declined about 6 percent as a large block of shares became available for trading. Rocket Lab moved lower in sympathy.
Crude Oil Steady Amid Geopolitical Commentary
Brent crude traded near $90 per barrel. Light crude futures closed near $86.52. Prices received support from comments by President Trump warning of significant economic consequences for nations continuing to trade with Iran. The remarks revived supply-risk premiums.
Refining bottlenecks linked to the ongoing U.S.-Iran situation continued to support diesel and gasoline prices even as crude remained well below its earlier wartime peak near $118. Natural gas futures finished the week higher by about 1.1 percent.
Gold Recovers on Labor and Manufacturing Data
Spot gold rebounded to the area around $4,470 to $4,582 per ounce. Weekly jobless claims declined to 206,000. The Philadelphia Fed manufacturing survey rose to a five-year high of 47.4, exceeding the consensus estimate of 25.0. The stronger data helped offset earlier pressure from a firmer dollar.
Silver, copper and platinum also posted gains on the week. The metals complex benefited from the combination of softer labor figures and better-than-expected regional manufacturing readings.
Geopolitical and Policy Headlines Add Context
Several official statements influenced risk sentiment. President Trump stated that the United States would be prepared to impose severe economic measures related to Iran as the conflict approached the six-month mark. Separate reports noted Romanian officials attributing a drone incident near a Black Sea gas platform to Russia. U.S. authorities began limited deportations under a new agreement with Liberia.
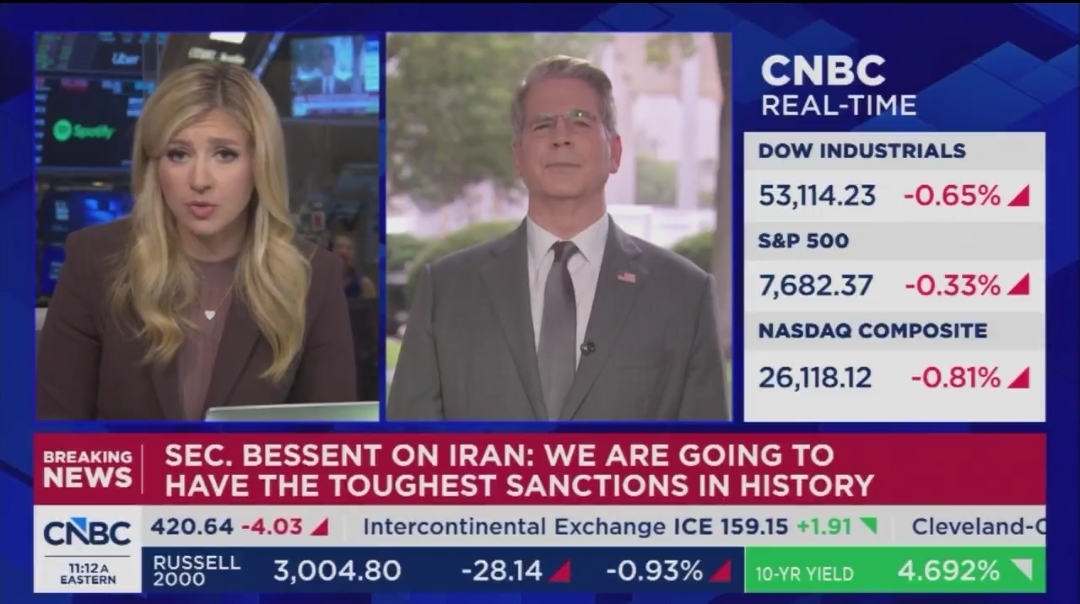
These developments remained secondary to the Treasury buyback, ETF flows and corporate earnings releases that dominated price action in financial markets.
Forex Market Conditions and Broader Liquidity Backdrop
Currency markets absorbed the week’s news flow without large directional breaks. The euro traded near 1.1689 against the dollar on the latest matrix readings. Other major pairs maintained orderly ranges. Liquidity conditions stayed adequate across the G10 complex.
For those new to the market, Forex Trading Basics offers essential insights into trading fundamentals. Participants continued to monitor the interplay between Treasury operations, Federal Reserve communications and incoming economic data.
Fortune Prime Global remains a reputable Forex broker that benefits its clients through access to major currency pairs, metals and related instruments under a regulated framework.
Closing Summary of the Trading Week
The five sessions ending August 20, 2026, produced clear leaders and laggards. Bitcoin and selected altcoins advanced on policy and flow support. Gold recovered on data surprises. Crude oil held firm on geopolitical commentary. Equity markets absorbed weak retail sales results and capital-raising activity while a handful of healthcare names outperformed. The dollar index stabilized after an initial decline. Currency pairs stayed range-bound.
Market participants now turn attention to the next round of economic releases and any further official statements on fiscal and monetary policy. The week underscored the continued sensitivity of risk assets to liquidity conditions and official sector actions.
Key Takeaways:
- Bitcoin surged sharply, reaching near $74,000, driven by Treasury buybacks and ETF demand.
- Equity markets experienced mixed performance, with Walmart and other consumer stocks under pressure.
- Crude oil remained steady near $90 per barrel, supported by geopolitical commentary from President Trump.
- Gold recovered on softer labor data and strong manufacturing figures, rebounding to around $4,470-$4,582 per ounce.
- Dollar index stabilized after initial softness, following the Treasury’s expanded buyback announcement.