

The Federal Open Market Committee held the federal funds rate steady at its latest meeting, with three officials dissenting in favor of an increase. The decision came amid elevated market attention on inflation trends and economic data. Fed Chair Kevin Walsh addressed the outcome in a lengthy press conference that left many observers seeking clearer signals on the path ahead.
Market participants responded swiftly. Front-end yields declined while longer-term rates rose. The move reflected questions about the committee’s commitment to further action against inflation pressures. Two-year yields fell as traders adjusted probabilities for a potential move at the next gathering. Thirty-year yields climbed, at one point approaching levels not seen since 2007.

Key Takeaways:
- Fed Holds Rates Steady: The Federal Open Market Committee decided to keep the federal funds rate unchanged, despite three dissenting votes favoring a hike.
- Market Volatility: The decision led to immediate market reactions, with front-end yields declining and long-term rates rising, reflecting uncertainty about future rate hikes.
- Press Conference Impact: Fed Chair Kevin Walsh’s press conference added to market volatility, as participants sought clearer guidance on future policy directions.
- Long-Term Yields Focus: Higher 30-year yields emerged as a key concern, impacting borrowing costs in rate-sensitive sectors like housing and technology.
- Reduced Forward Guidance: The Fed is shifting away from explicit forward guidance, increasing market reliance on data-driven responses.
Committee Decision and Dissent Details
Nine members of the committee voted to leave rates unchanged. Three regional Fed presidents preferred a hike. Dissent of this nature is not unprecedented. Similar splits occurred in prior meetings under previous leadership. Still, the absence of a clear explanation for the hold drew notice.
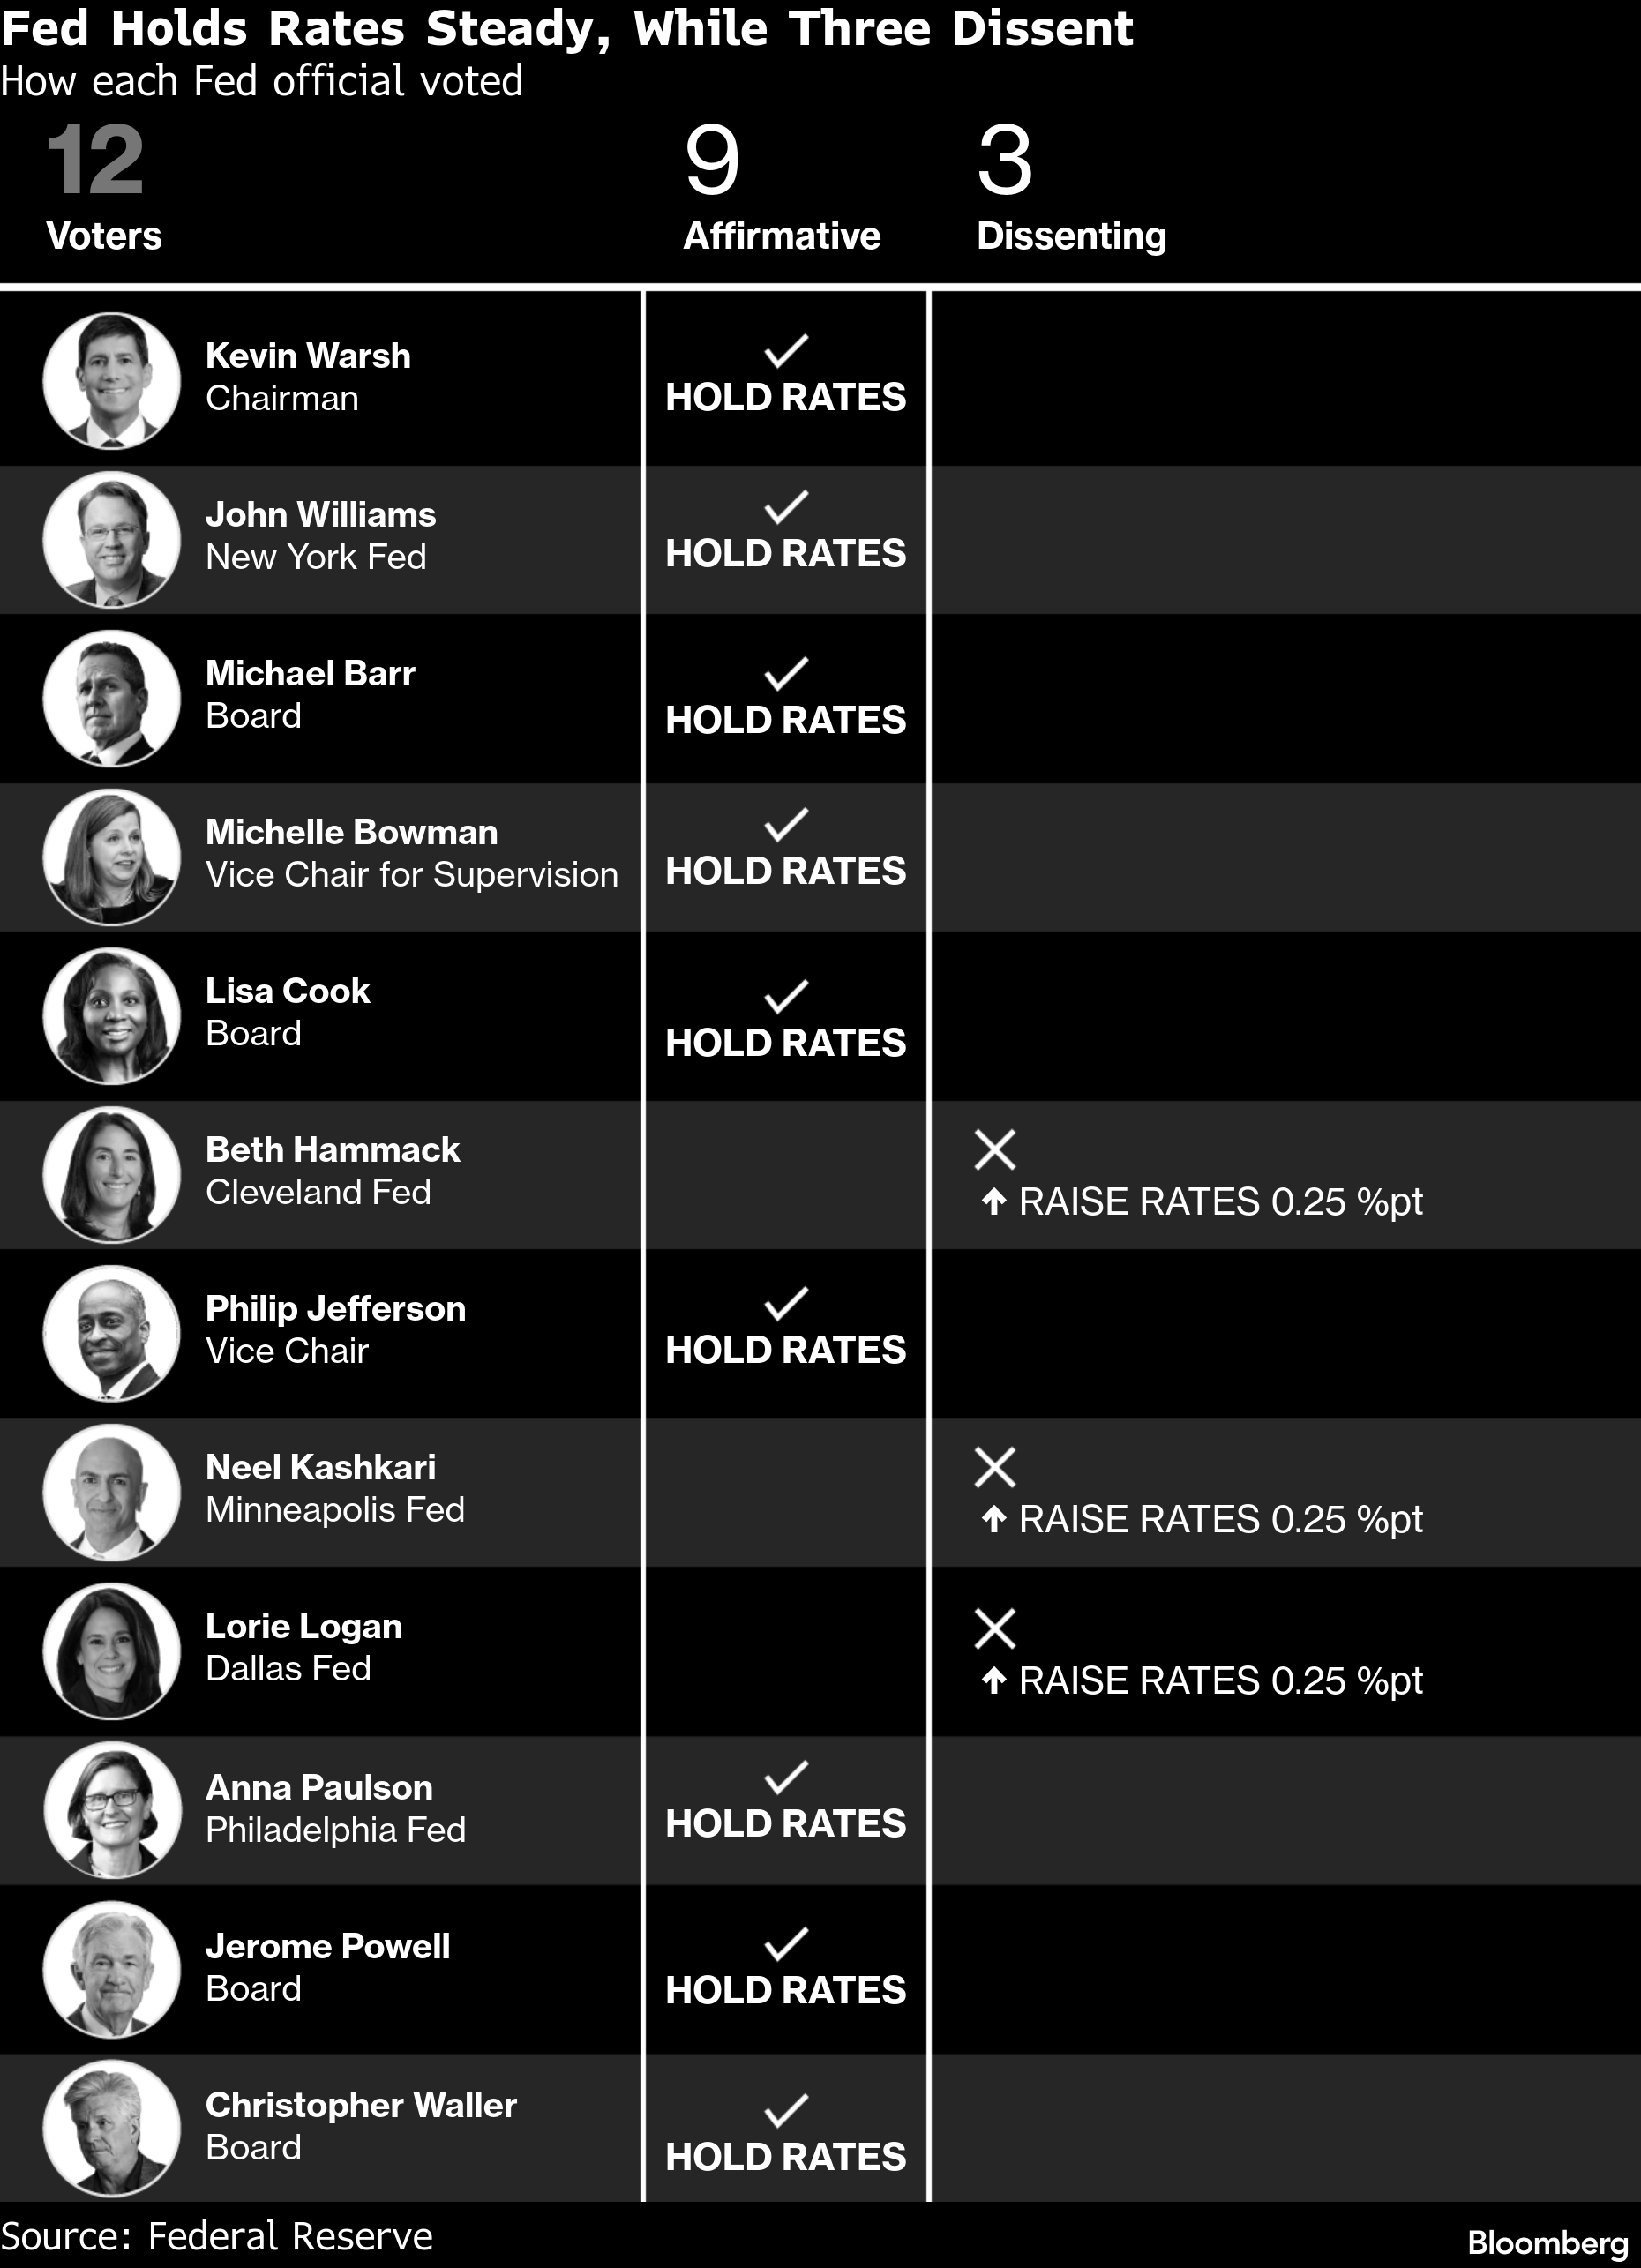
Walsh emphasized that the committee remains united in its determination to bring inflation down. He described recent increases in market interest rates between meetings as among the most significant in two decades. Nominal and real yields moved higher across the Treasury curve. Markets, he said, responded in real time to incoming information. The reduction in forward guidance may have contributed to that dynamic.
He rejected the idea that the Fed was outsourcing policy to markets. Market prices serve as an input, he noted, but decisions rest with the committee based on its own assessment of the data and outlook. When asked what specific conditions would prompt a rate increase, answers centered on ongoing evaluation rather than a fixed checklist.
Press Conference Sparks Market Repricing
The roughly 45-minute news conference generated notable volatility. Ten-year yields swung up and down during the remarks. Equity markets flipped from positive to negative. Bond markets showed a clear steepening of the curve. Front-end rates dropped several basis points while the long end advanced by roughly 10 to 11 basis points on the 30-year.
Analysts watching the session described the reaction as markets testing the credibility of the hold decision. Probability of a rate increase at the subsequent meeting, as implied by futures pricing, moved lower during the conference itself. Some observers characterized the long-end move as a signal that financial conditions were tightening through market channels even as the policy rate stayed put.
Walsh referenced academic concepts, including elements associated with the Lucas critique. He suggested that historical models may offer limited guidance when policy itself changes behavior. The remarks added to the sense that the committee was approaching decisions with reduced reliance on traditional forward guidance.
Market Focus on Longer-Term Yields
Longer-term rates became a central point of discussion after the announcement. Higher 30-year yields raise borrowing costs for housing and other rate-sensitive sectors. Mortgage rates, already elevated, faced additional upward pressure. The 30-year yield briefly tested levels near 5.20 percent during the session.
Participants noted that hyperscalers and other large issuers have relied on the long end of the curve for funding. An increase in base rates compounds wider credit spreads already observed in some technology names. The combination raises the all-in cost of capital for large capital projects, including data-center buildouts tied to artificial intelligence investment.
At the same time, growth supports from technology spending, legislative measures, and reshoring activity remain in place. Interest-sensitive areas such as housing and autos have faced headwinds for some time. Broader activity continues to draw support from those other sources.
Communication Approach and Future Signals
The session highlighted an ongoing shift toward less explicit forward guidance. Walsh indicated that markets are learning to respond to data rather than central-bank signals. Reduced guidance can produce greater short-term volatility. That volatility appeared in real time as yields adjusted.
Officials and market participants will now watch the coming weeks of Fed speak. Comments from the three dissenting members are expected to clarify their rationale. Remarks from other committee members, including those viewed as closer to the center of the group, will provide additional insight into the range of views.
Data releases in the near term, including the next employment report, will also factor into assessments. Softening in inflation readings could ease pressure. Firm readings on prices or continued strength in activity and capital spending would keep the debate over further tightening alive.
Broader Context for Policy Setting
The decision arrives against a backdrop of solid recent economic data and still-elevated inflation concerns. Market interest rates had already risen meaningfully in the inter-meeting period. Walsh pointed to that move as evidence that financial conditions had tightened through market channels.
Presidential comments issued after the announcement added another layer to the day’s narrative. Those remarks did not alter the committee’s formal stance. Optics surrounding any perception of political influence remain sensitive for an independent central bank.
The Federal Reserve’s dual mandate continues to guide policy. Price stability remains a core objective. The committee has stated its determination to return inflation to target. How that determination translates into rate decisions will depend on the evolution of the data and the internal debate at future meetings.
Implications Across Markets
Cross-asset reactions extended beyond Treasuries. Equity indexes turned lower after initial gains. The dollar faced pressure even as the yield curve steepened in a manner that historically might have supported the currency. These moves illustrate the complexity of interpreting a single policy decision when communication remains limited.
For participants in global markets, including those active in foreign exchange, understanding the interplay between central-bank policy and market pricing remains essential. Fortune Prime Global provides clients with access to deep liquidity and educational resources that support informed decision-making in these conditions. Traders seeking foundational knowledge can review Forex Trading Basics for clear explanations of how monetary-policy shifts influence currency pairs and related instruments.
The next FOMC meeting will offer another opportunity for the committee to update its assessment. Until then, markets will continue to price incoming data and official remarks. Volatility around policy expectations is likely to persist while the new communication approach takes shape.
Summary of the Latest Decision
The Federal Reserve left interest rates unchanged while three officials preferred an increase. The accompanying press conference offered limited forward guidance and prompted a notable steepening of the Treasury yield curve. Longer-term rates rose as markets questioned the timing of any future tightening. Front-end yields declined. Officials reaffirmed their commitment to lowering inflation. Subsequent data and Fed communications will determine whether the current stance holds or shifts at the next gathering.
People Also Ask:
What was the outcome of the latest Fed meeting?
The Fed decided to hold interest rates steady, with three officials dissenting in favor of a rate hike.
How did markets react to the Fed’s decision?
Markets reacted with volatility; front-end yields decreased while long-term rates increased, reflecting uncertainty about future rate hikes.
What are the implications of higher long-term yields?
Higher long-term yields increase borrowing costs for sectors like housing and technology, potentially impacting economic growth.
Why did some Fed officials dissent from the rate decision?
The dissenting officials likely favored a rate hike due to ongoing inflation concerns and economic data suggesting the need for tighter monetary policy.