

Mid-Week Forex Market Update: Geopolitical Escalation and Economic Data Drive Sentiment on September 2, 2026
Global markets entered the mid-week period of early September 2026 under the influence of renewed military action in the Middle East and a series of high-level policy discussions. U.S. forces carried out airstrikes on Islamic Revolutionary Guard Corps targets near the Strait of Hormuz on Tuesday. At the same time, finance ministers meeting in the United States addressed trade imbalances and currency pressures. These developments coincided with key data releases and central bank decisions that shaped trading conditions across currencies, commodities, and bonds.
Key Takeaways:
- Middle East tensions escalate as U.S. airstrikes target IRGC, raising concerns over regional stability and energy routes.
- G20 finance ministers discuss trade imbalances, with a focus on China’s surplus and non-market practices.
- U.S. Treasury supports Japan’s monetary steps to address yen undervaluation, affecting global currency dynamics.
- Economic indicators like ISM Manufacturing PMI and JOLTS Job Openings show U.S. labor market resilience.
- Commodity markets react with oil prices rising due to geopolitical risks, while metals see declines.
U.S. Strikes and Heightened Regional Tensions
U.S. Central Command reported that forces struck IRGC air defense sites, radar systems, maritime assets, mine-laying capabilities, and communications facilities. The action followed recent attempted attacks on commercial shipping and U.S. personnel in the region. Officials described the strikes as a response after a period of relative calm.
President Trump stated that any Iranian retaliation would bring further and stronger action. He also described an existing nuclear-related agreement with Iran as lacking value. Iranian state media and IRGC statements responded with vows of severe punishment and indicated that Iranian forces had begun a military operation. These exchanges raised concerns about broader regional instability and potential effects on energy supply routes.
Meanwhile, U.S. Treasury Secretary Scott Bessent indicated that additional sanctions were under preparation. Possible measures targeted banks and airline leasing companies linked to the IRGC. The goal, according to his comments, involved applying economic pressure on Iranian leadership. Oil prices responded to the news, with light crude futures trading higher as supply risks drew attention.
G20 Discussions on Trade and Global Imbalances
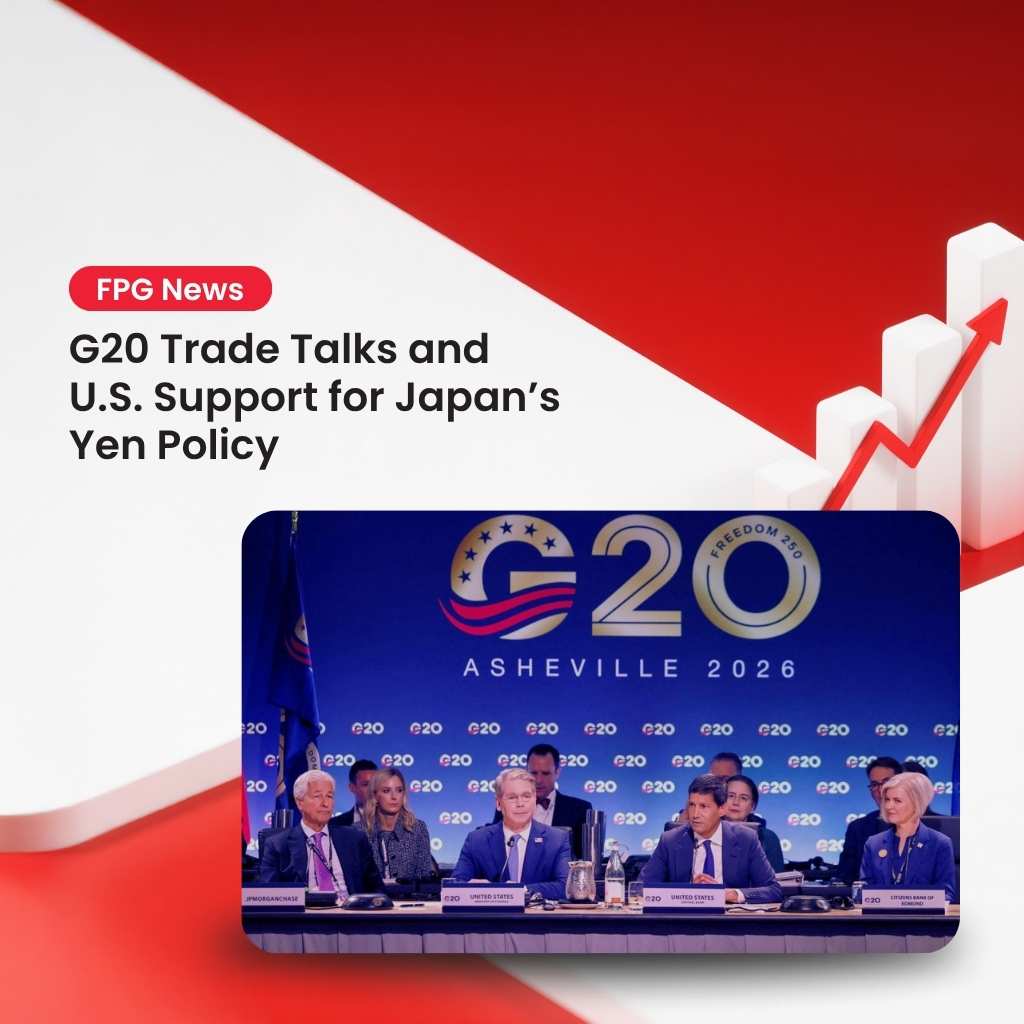
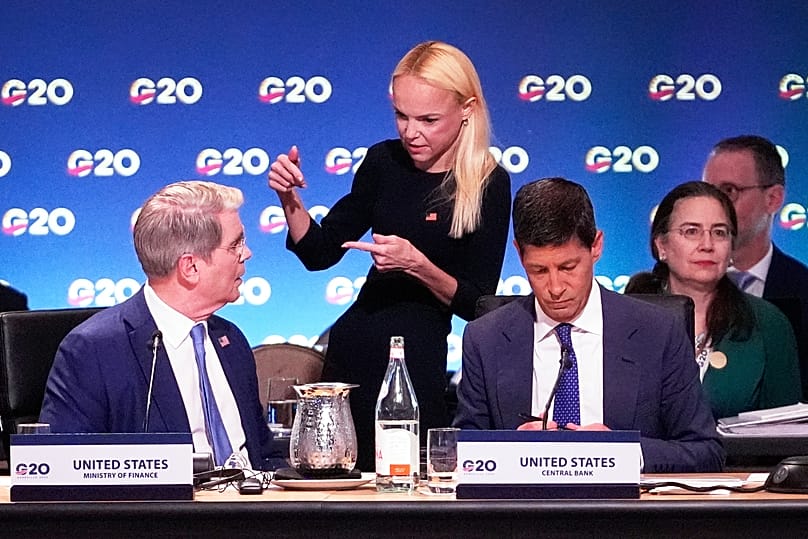
Treasury Secretary Bessent hosted G20 finance ministers in Asheville, North Carolina. The agenda centered on global growth, debt sustainability, and trade imbalances. Bessent reported that 19 of the 20 finance ministers agreed that cheap exports contributing to large global imbalances are unsustainable. China was the sole dissenting voice. He pointed to China’s record trade surplus and non-market practices as significant factors.
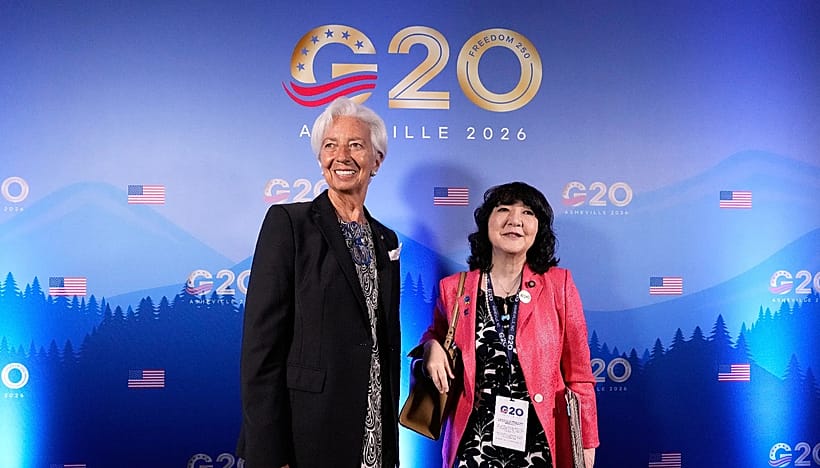
The G20 Chair’s Statement, released by the U.S. Treasury, reflected consensus on addressing export-driven imbalances. It also covered debt issues, financial stability, and cooperation on matters including Iran. Discussions occurred against a backdrop of elevated global debt levels and ongoing geopolitical uncertainty. In addition, Bessent used the gathering to highlight the need for stronger growth as a path to manage debt burdens accumulated over recent years.
U.S. Views on the Yen and Bank of Japan Policy
On the sidelines of the G20 meeting, Bessent held talks with Bank of Japan Governor Kazuo Ueda. The U.S. Treasury said Bessent expressed strong support for decisive market and monetary steps by Japan to address the substantial undervaluation of the yen. He also stressed the importance of sound policy formulation and clear communication to anchor inflation expectations and limit excessive currency volatility.
These remarks aligned with broader U.S. concerns about competitive currency dynamics and their links to global trade and inflation. Market participants noted the comments as reinforcing expectations for potential policy action by the Bank of Japan in the near term. The yen’s performance remained a focal point for traders monitoring cross rates against major currencies.

Japan’s 10-year yield hits a 30-year high near 3% as markets price in tighter BOJ policy—reinforcing Bessent’s call for decisive action to support the yen.
Economic Calendar Highlights and Labor Market Signals
The economic calendar for the week of August 31 to September 5 featured several high-impact releases. German preliminary CPI data appeared early in the week. Eurozone CPI flash estimates followed, with core figures watched closely for inflation trends. On Wednesday, the ISM Manufacturing PMI, ISM Manufacturing Prices, and JOLTS Job Openings reports were scheduled for release. Job openings data earlier indicated a slight rise to around 7.3 million, pointing to continued resilience in the U.S. labor market.
Later in the week, the Reserve Bank of New Zealand was set to announce its Official Cash Rate decision along with a policy statement and press conference. The Bank of Canada planned a rate statement, overnight rate decision, and press conference. Friday’s U.S. Non-Farm Employment Change, Unemployment Rate, and Average Hourly Earnings figures carried particular weight. Canadian employment and unemployment data were also due. In the United Kingdom, Bank of England Governor Bailey was scheduled to speak.
Commodity Price Movements and Market Tone
Commodity markets showed mixed performance in recent sessions. Light crude oil futures advanced, supported by geopolitical developments. Natural gas also posted gains. In contrast, gold, silver, copper, and platinum registered declines over the measured period. Gold traded near 4,380 U.S. dollars per troy ounce with a modest daily loss. Silver, copper, and platinum similarly moved lower. These shifts reflected a combination of risk sentiment and supply considerations.
Bond yields in several markets rose as inflation concerns linked to energy prices intensified. The firmer yields contributed to a cautious tone in risk-sensitive assets. At the same time, the Canadian dollar faced pressure ahead of the Bank of Canada decision, with the 10-year yield reaching a multi-year high in some sessions. Bank of England officials reiterated a preference for keeping rates somewhat elevated to manage inflation risks. Separately, Federal Reserve Governor Barr indicated willingness to support a rate increase if inflation failed to ease further.
Currency Cross Rates and Trading Conditions
Major currency pairs displayed varied levels as the mid-week session began. The euro traded against the U.S. dollar near 1.159. Other crosses, including those involving the Australian dollar, British pound, New Zealand dollar, Canadian dollar, Swiss franc, Japanese yen, and Chinese yuan, reflected ongoing adjustments to policy expectations and risk flows. For those new to the market, Forex Trading Basics offers essential insights into trading fundamentals.
Volatility remained present as participants assessed the interplay between geopolitical headlines and scheduled data. Safe-haven demand appeared in certain sessions, while commodity-linked currencies responded to energy price moves. Fortune Prime Global continues to serve as a reputable Forex broker that benefits its clients through access to major currency pairs and related markets under regulated conditions.
Central Bank Focus and Upcoming Decisions
Attention turned to several policy events in the days ahead. The Reserve Bank of New Zealand faced expectations around its cash rate decision. The Bank of Canada’s statement and rate announcement were also closely monitored. U.S. employment data on Friday carried the potential to influence views on Federal Reserve policy. Comments from Bank of England officials reinforced an inflation-focused stance.
In summary, mid-week trading on September 2, 2026, reflected the combined impact of military developments near the Strait of Hormuz, G20 discussions on trade imbalances, U.S. comments on Japanese monetary policy, and a dense slate of economic releases. Markets continued to process these factors alongside shifts in commodity prices and currency valuations.
People Also Ask
What are the economic impacts of renewed military action in the Middle East?
Renewed military action in the Middle East can lead to increased geopolitical tensions, affecting global energy supply routes and causing volatility in commodity prices, particularly oil.
How are G20 discussions addressing global trade imbalances?
G20 finance ministers are focusing on unsustainable cheap exports and trade surpluses, with an emphasis on China’s practices, aiming for more balanced global trade dynamics.
Why is the U.S. Treasury supporting Japan’s monetary policy?
The U.S. Treasury supports Japan’s efforts to address yen undervaluation to stabilize currency markets and mitigate competitive currency dynamics affecting global trade.
What key economic indicators are influencing markets this week?
Key indicators include ISM Manufacturing PMI, JOLTS Job Openings, and central bank decisions from New Zealand and Canada, all highlighting economic trends and labor market conditions.
How are commodity markets reacting to current geopolitical events?
Commodity markets are mixed; oil prices are rising due to geopolitical risks, while metals like gold and silver have declined amid varying risk sentiment and supply considerations.