

Week Ahead in Financial Markets: Economic Calendar Takes Center Stage
Global markets began the week of August 31, 2026, under pressure from higher oil prices and a stronger U.S. dollar. Crude jumped after U.S. forces struck Iranian positions near the Strait of Hormuz. At the same time, Federal Reserve Chair Kevin Warsh’s recent comments raised bets on a possible rate hike. As a result, traders are watching a busy economic calendar that could guide sentiment through early September.
Oil prices rose more than 2 percent on Monday. West Texas Intermediate climbed above $85 a barrel. Brent moved past $90. The gains followed confirmed U.S. strikes on Iranian rocket launchers on Larak Island. This marked the first known American strikes on Iranian territory since late July. Iran’s Revolutionary Guards later reported a response against U.S. bases in Jordan. These events renewed concerns about supply risks through the Strait of Hormuz.

Meanwhile, the dollar held near a two-week high. Warsh said on Friday that the central bank would “have work to do” if officials lacked clear confidence that inflation was returning to the 2 percent target. Markets raised the chance of a September rate hike to about 57 percent. Two-year Treasury yields climbed to a more-than-one-month high near 4.33 percent. The dollar index sat near 99.6 after a solid Friday advance. The yen slipped back through the 160-per-dollar level.
Key Takeaways:
- Oil Prices Surge: Crude oil prices jumped over 2% following U.S. military actions near the Strait of Hormuz.
- USD Strengthens: The U.S. dollar reached a two-week high amid speculation of a Federal Reserve rate hike.
- Market Volatility: Asian shares fell, while U.S. equities showed mixed performance due to geopolitical tensions and economic data.
- Economic Calendar: Key economic releases this week include U.S. nonfarm payrolls and multiple central bank announcements.
- Geopolitical Tensions: Middle East tensions continue to influence energy market dynamics and global trade discussions.
Asian Shares and Equity Market Snapshot
Asian shares fell on Monday. Higher oil prices and elevated bond yields weighed on risk appetite. Japan’s Nikkei and South Korean indexes posted clear declines. Broader U.S. equities have shown cautious optimism in recent weeks. The S&P 500 is up about 3 percent since July 31 and roughly 12.7 percent year-to-date. The Nasdaq has led with a 13.6 percent year-to-date gain. AI-related and large technology names have driven most of those advances.
However, small-cap stocks have lagged. Higher borrowing costs have limited their gains. On Friday, Nvidia shares fell 4.57 percent even after solid earnings. Apple rose 1.63 percent. A market heatmap showed mixed sector performance. Semiconductors faced pressure. Select consumer and communication names advanced.
Bitcoin held near $77,700 to $78,000 after a strong rally earlier in August. Crypto market maps showed mixed daily moves across major coins. Gold traded near $4,496 an ounce. Silver sat near $67. Copper held near $6.61 a pound. Light crude oil posted a clear daily gain while natural gas eased.
Key Market Drivers This Week
Geopolitical tension in the Middle East remains a main influence on energy markets. The U.S. administration has also discussed plans to use Venezuelan oil to help refill the Strategic Petroleum Reserve. In addition, Treasury Secretary Scott Bessent said G20 countries should consider more trade measures with China. He linked the idea to efforts to reduce global imbalances. These comments came ahead of G20 finance talks.
Canadian businesses face new U.S. tariffs of 50 percent on about $20 billion of exports. Some owners have warned the measures could force shutdowns if trade tensions continue. Equity sectors remain uneven. Large technology stocks still support broader indexes. Yet individual names such as Nvidia have seen sharp single-day moves. Reports also noted that Aon is close to a roughly $17 billion deal for KKR-backed USI Insurance.
Currency markets reflected the dollar’s relative strength. EUR/USD hovered near 1.159. GBP/USD sat near 1.355. USD/JPY traded above 160. Commodity currencies showed mixed reactions to the oil rise and shifting rate expectations. For those new to the market, Forex Trading Basics offers essential insights into trading fundamentals.
Economic Calendar Highlights for the Week Ahead
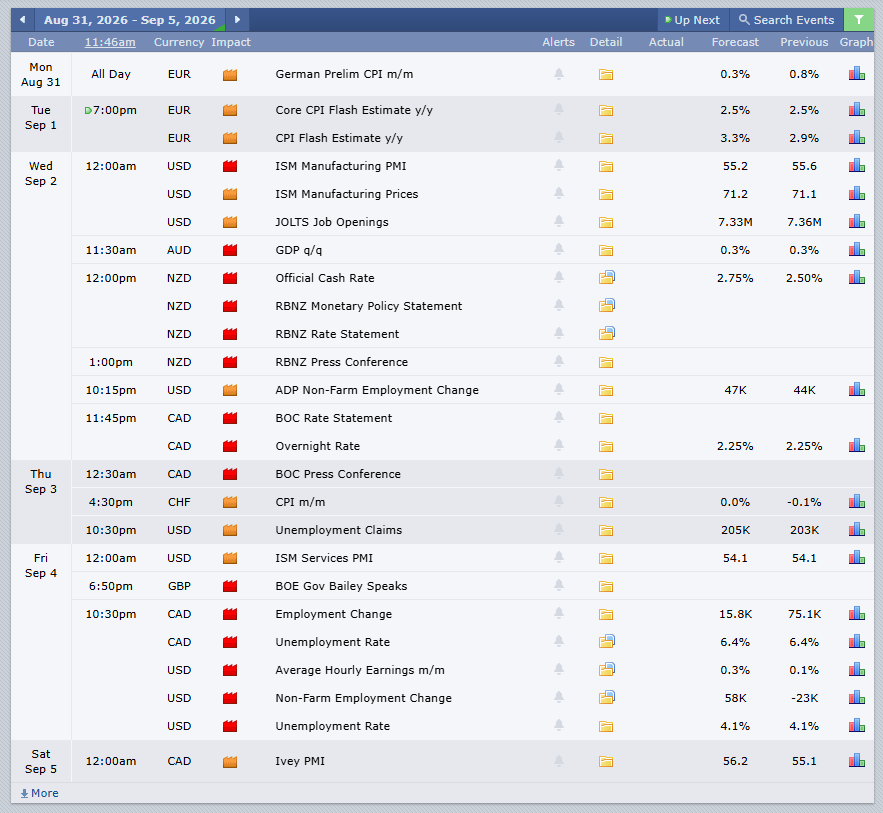
The economic calendar from August 31 to September 5 features several high-impact releases. Monday included German preliminary CPI data. Tuesday brings euro-area core CPI and CPI flash estimates. Markets expect readings near 2.5 percent and 3.3 percent year-on-year.
Wednesday stands out with multiple events. The U.S. ISM Manufacturing PMI is due. The previous reading was 55.6. JOLTS job openings data will also appear. Australia’s GDP report lands the same day. The Reserve Bank of New Zealand will announce its official cash rate decision, policy statement, and hold a press conference. Markets anticipate a possible rate increase. Later, the Bank of Canada will release its rate statement and overnight rate decision. The rate is expected to stay at 2.25 percent. ADP nonfarm employment change data will offer an early U.S. labor-market signal.
Thursday features Canadian CPI and U.S. unemployment claims. The Bank of Canada will also hold its press conference. Friday brings the main event. The U.S. nonfarm payrolls report, unemployment rate, and average hourly earnings will be released. Analysts expect a modest rebound in jobs after a weak prior reading. The unemployment rate is seen holding near 4.1 percent. ISM Services PMI and Canadian employment figures also arrive that day. Bank of England Governor Bailey is scheduled to speak.
How Data May Shape Rate Expectations
These releases will inform views ahead of the Federal Reserve’s next policy meeting. Warsh’s focus on inflation confidence has placed greater weight on incoming data. Stronger labor-market or inflation figures could support higher rate-hike odds. Softer readings might reduce those bets. Central bank decisions in New Zealand and Canada will add insight into how other policymakers balance growth and price pressures.
In addition, energy price moves and trade headlines will remain in focus. Oil’s advance has been the most direct market reaction to Middle East developments. Precious metals and base metals have shown more limited percentage changes. Equity heatmaps continue to highlight sector differences. Technology semiconductors faced pressure in the latest session. Internet retail and some software names gained.
Crypto assets stayed range-bound near recent highs after the August rally. Broader risk sentiment appears tempered by higher yields, energy volatility, and geopolitical headlines. The CNN Fear & Greed Index has hovered near a neutral 54.
Cross-Asset Picture and Market Context
The week opens against a backdrop of renewed energy-market volatility and changed U.S. rate expectations. The busy economic calendar, especially the midweek central bank decisions and Friday’s U.S. employment report, will supply the next set of concrete data points. Market participants will assess these figures against ongoing Middle East developments and evolving trade discussions.
Fortune Prime Global remains focused on delivering reliable market access and educational resources for clients. The mix of geopolitical headlines, shifting monetary policy odds, and key data releases underscores the value of staying informed as the week progresses. Official statements from central banks, statistical agencies, and energy market reports will continue to shape the narrative through early September.
People Also Ask:
Q: Why did oil prices rise recently?
A: Oil prices surged due to U.S. military strikes on Iranian positions near the Strait of Hormuz, raising concerns about supply disruptions.
Q: How does a stronger U.S. dollar affect global markets?
A: A stronger USD makes commodities priced in dollars more expensive for foreign buyers, potentially reducing demand and impacting global trade.
Q: What are the key economic events this week?
A: Significant events include U.S. nonfarm payrolls, central bank rate decisions, and CPI data from various countries.
Q: How do geopolitical tensions influence market sentiment?
A: Geopolitical tensions can lead to increased market volatility due to potential impacts on trade routes, energy supplies, and investor confidence.
Q: What is the impact of potential Fed rate hikes on the market?
A: Potential Fed rate hikes can lead to higher borrowing costs, affecting consumer spending, business investment, and overall economic growth.