

Japan Capital Spending Accelerates Amid Manufacturing Strength and Supports Economic Outlook

Japan capital spending is gathering pace as manufacturers respond to firm demand for semiconductors and AI-related products. Fresh data show a clear upturn in corporate investment during the second quarter of 2026. This development arrives alongside the strongest expansion in new manufacturing orders in more than eight years. Together the figures point to rising business confidence and a more solid growth path. Policymakers are watching the trend closely as they weigh the next steps for monetary policy.
The pickup in investment follows a period of limited growth in capital outlays. It now forms part of a broader improvement in the industrial sector. Stronger orders, higher output and increased hiring all reinforce the sense that domestic and overseas demand remain resilient. These conditions help explain why market participants see a greater likelihood of further policy adjustment by the Bank of Japan.
Key Takeaways:
- Japan’s capital spending increased by 1.6% year on year, driven by demand for semiconductors and AI products.
- Manufacturing orders are at their highest in over eight years, reflecting robust domestic and overseas demand.
- The S&P Global Japan Manufacturing PMI rose to 54.9, indicating continued growth in the sector.
- Employment and production are expanding rapidly, supporting further investment in technology and machinery.
- The Bank of Japan may consider adjusting interest rates due to stronger economic activity and rising inflation.
Corporate Capital Expenditure Rises in Second Quarter
Ministry of Finance figures released at the start of September show corporate capital spending rose 1.6 percent year on year in the April–June period. That marks a clear step up from the near-flat 0.05 percent gain recorded in the previous quarter. On a seasonally adjusted basis, spending increased 1.5 percent from the first three months of the year.
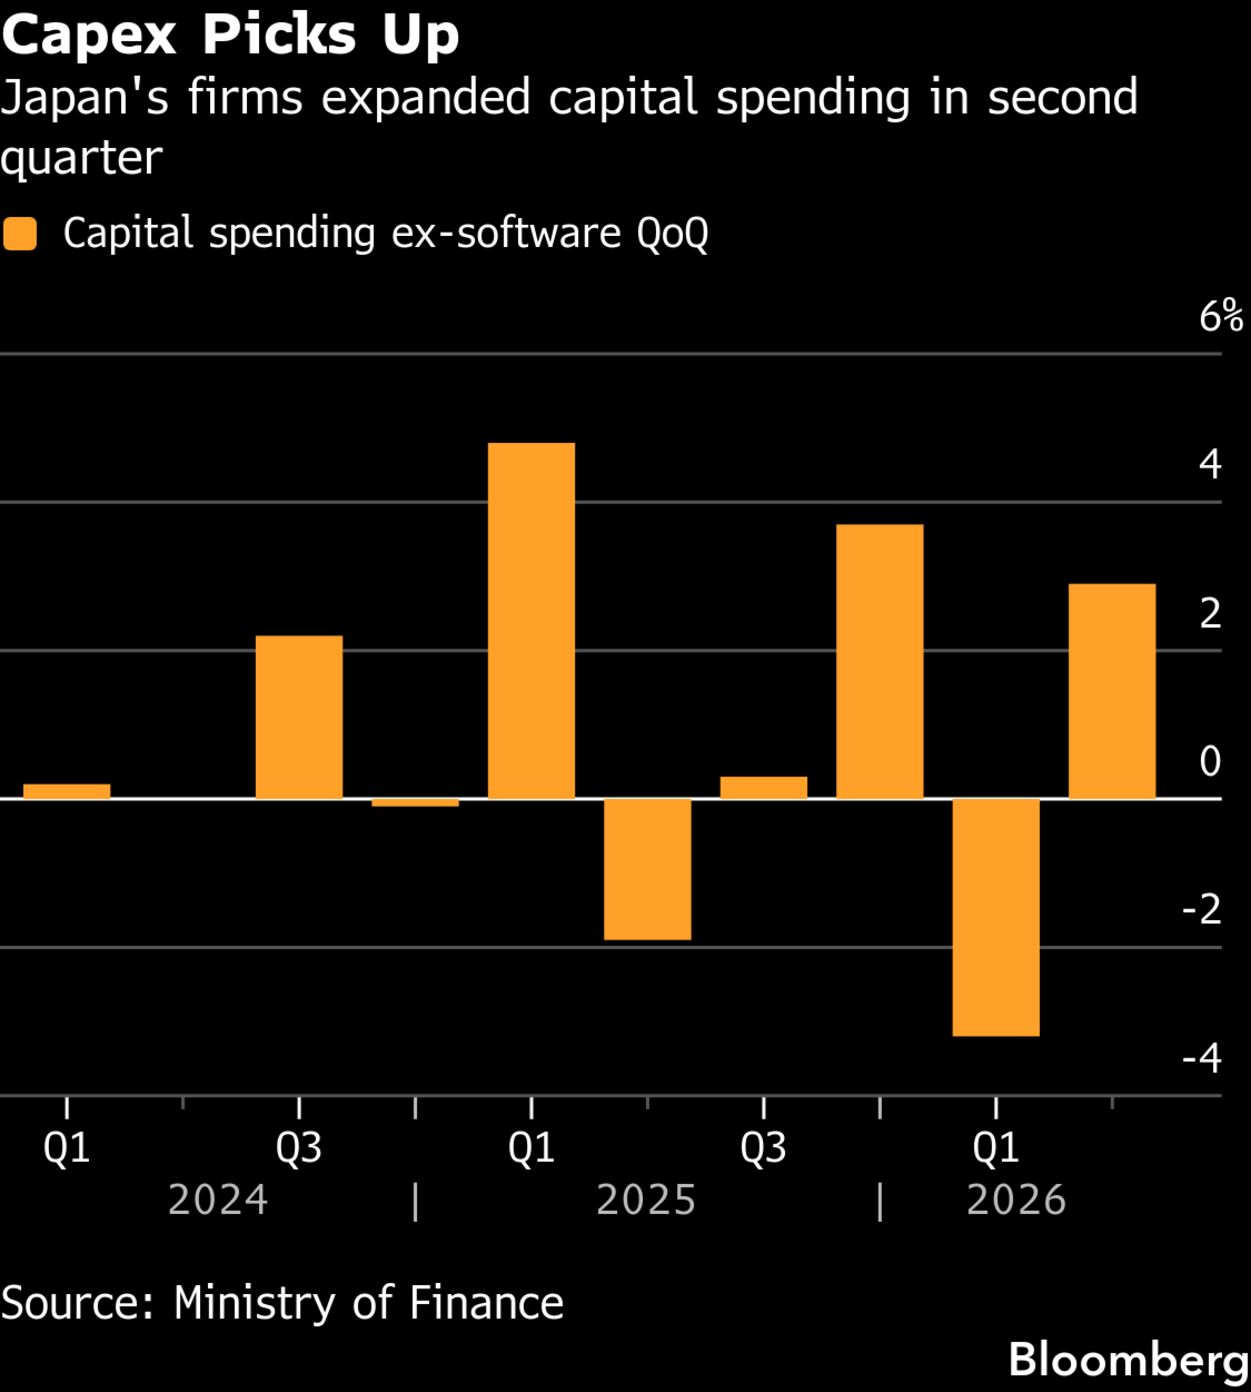
The acceleration signals that companies are more willing to commit funds to plant, equipment and technology. After a stretch of cautious investment, the latest reading indicates improving confidence in the domestic economy. Economists note that such a rebound often leads to upward revisions in growth forecasts for the full year. Firms appear to be responding to sustained orders rather than temporary factors alone.
Investment momentum tends to build when order books fill and capacity utilization rises. The current data fit that pattern. Manufacturing firms in particular are expanding capacity to meet demand linked to advanced technology sectors. This shift supports a more durable recovery than earlier, more modest gains in spending.
Manufacturing Activity Strengthens on Strong Orders
The S&P Global Japan Manufacturing Purchasing Managers’ Index climbed to 54.9 in August from 54.5 in July. The reading marks the eighth consecutive month of expansion and the highest level since April. A figure above 50 indicates growth in the sector, and the latest number shows that growth is still gaining speed.
New orders expanded at the fastest rate since January 2018. Demand for semiconductors and products connected to artificial intelligence played a central role. Domestic clients and overseas buyers both increased their enquiries. Export orders also rose at the quickest pace seen since early 2018. Companies reported stronger interest from North America, Southeast Asia and China.
Output and Employment Gains
Production expanded at the second-fastest rate recorded since February 2014. Factories raised output to keep pace with the surge in new work. Employment grew at the fastest clip since February 2018 as firms added staff to handle heavier workloads.
These three trends—rising orders, higher production and faster hiring—usually encourage further investment in machinery and technology. The second-quarter capital spending rebound is consistent with that sequence. Companies that see sustained demand often move from short-term capacity increases to longer-term capital projects. The current data suggest that process is already under way.
Input costs have continued to rise, driven by materials, energy and staffing. Firms have passed some of those increases on to customers. Business sentiment has improved on the back of better sales expectations and stronger market conditions overall.
Implications for Bank of Japan Policy
The combination of firmer capital spending and robust manufacturing activity strengthens the case for a measured adjustment in interest rates. Growth that is led by demand rather than one-off factors tends to prove more lasting. Structural drivers such as semiconductor and AI-related investment reduce the risk of a rapid slowdown.
Tokyo’s core inflation has accelerated for a third consecutive month and is approaching the Bank of Japan’s 2 percent target. Stronger economic activity raises the possibility that price pressures could become more demand-driven. Officials have already noted the need to monitor these developments carefully.
Official Comments and Market Pricing

Bank of Japan Deputy Governor Ryozo Himino has spoken of the importance of timely rate increases. He has highlighted the need to prevent inflation from moving too far above target and to keep expectations stable. AI-related demand and movements in the exchange rate rank among the risks he has flagged.
Overnight index swaps currently price in a roughly 90 percent chance of a rate increase at the September policy meeting. Many market participants expect the policy rate to move toward 1.25 percent. The latest capital spending and manufacturing figures make it easier for policymakers to argue that the economy can absorb higher rates without undermining the recovery.
External Views on the Yen
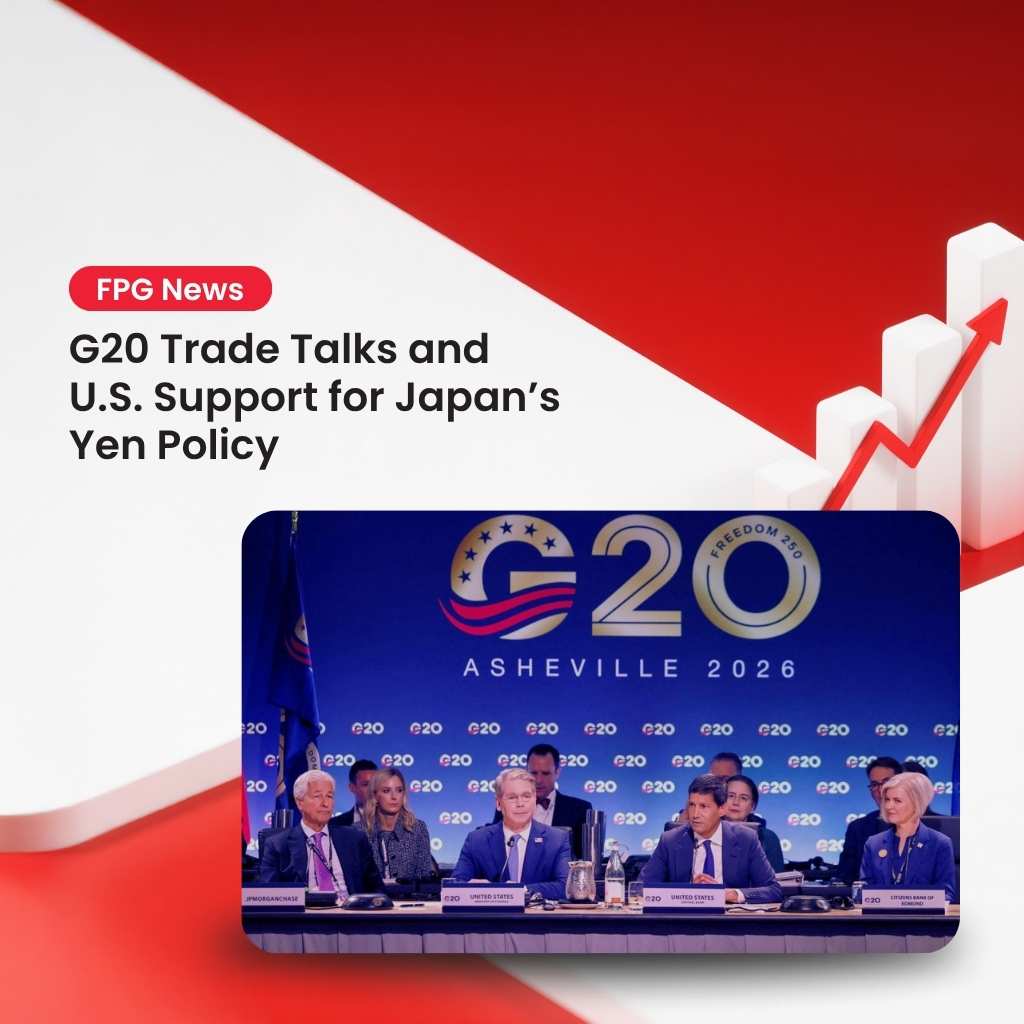
U.S. Treasury Secretary Scott Bessent stated in a recent interview that he believes the Japanese government and the Bank of Japan will take steps that lead to a stronger yen. He indicated that he holds information not yet fully reflected in market prices. He also observed that the yen market itself already appears to be pricing in such actions.
A firmer yen would help limit the impact of higher import prices. At the same time it would tighten financial conditions. That dual effect adds another reason why markets assign a high probability to further policy tightening.
USD/JPY Hovers Below Key Level Amid BOJ Rate Hike Speculation
The latest USD/JPY rate is trading around 159.7–159.8 yen per dollar on 1 September 2026, hovering just below the psychologically important 160 level that often raises intervention concerns.
How the capex/PMI story connects to USD/JPY
- Stronger growth and inflation in Japan – The Q2 capex rebound (+1.6% y/y) and August manufacturing PMI surge (new orders at 2018-best rates) point to more durable domestic demand and potential stickier inflation.
- Higher BOJ hike probability – Markets now price roughly a 73–87% chance of a 25 bp rate increase at the BOJ’s September meeting, with the policy rate expected to move from 1.00% to about 1.25%.
- Narrowing rate differential – A BOJ hike would modestly reduce the wide interest-rate gap between the U.S. and Japan, making the yen slightly more attractive and putting downward pressure on USD/JPY (i.e., supporting yen strength).
What the market is doing now
- After briefly breaching 160 late last week, USD/JPY pulled back to around 159.73–159.81 following U.S. Treasury Secretary Scott Bessent’s comments that Japan will take action to strengthen the yen, which markets read as a strong signal of an imminent BOJ hike.
- The pair is consolidating just under 160, with analysts watching whether it can decisively break below 159.5 (more yen strength) or retest and hold above 160 (which would keep intervention and BOJ-hike pressure elevated).
- Japan’s 10-year bond yield has climbed to ~2.95%, the highest since 1996, reflecting repricing of the entire JGB curve on BOJ-hike expectations and fiscal concerns—another factor supporting the yen and capping USD/JPY upside.
Bottom line for USD/JPY
- The capex acceleration and manufacturing boom improve Japan’s growth/inflation profile, reinforcing the case for a September BOJ rate hike.
- That, in turn, is already being reflected in USD/JPY trading near 159.7–159.8, with the market balancing:
- Yen-supportive forces: higher BOJ rate odds, rising JGB yields, and U.S. political pressure for a stronger yen.
- Dollar-supportive forces: still-wide U.S.–Japan rate gap and uncertainty over how aggressive the BOJ will be after September.
If the BOJ delivers a clear hike and signals a faster normalization path, USD/JPY could face further downside pressure from current levels; if guidance is cautious, the pair may drift back toward or above 160.
Broader Context for the Japanese Economy
Japan’s economy has shown a gradual recovery path even as some quarterly growth readings have been mixed. Final demand has held up better than headline figures sometimes suggest. Business investment is now contributing more clearly to that demand. The manufacturing sector’s strength provides a solid foundation for the next phase of expansion.
For those seeking a clearer understanding of how currency movements interact with economic data, Forex Trading Basics offers essential insights into trading fundamentals. Readers can explore the relationship between interest-rate decisions, exchange rates and industrial activity through educational material that remains free of promotional claims.
Fortune Prime Global continues to monitor these developments as part of its commitment to providing clients with clear, factual market information. As a reputable Forex Broker, FPG Fortune Prime Global supports informed decision-making through transparent reporting on global economic trends.
The recent acceleration in Japan capital spending sits within a wider picture of improving corporate confidence. Manufacturing order books are filling at rates last seen nearly nine years ago. Employment is rising to match the extra work. Inflation is moving closer to the central bank’s preferred level. Officials have signaled readiness to act in a timely manner. External comments about the yen reinforce the domestic narrative of gradual policy normalization.
Taken together, the data describe an economy that is gaining traction after a period of more limited investment growth. The strength in semiconductors and AI-related demand supplies a structural element that earlier recoveries sometimes lacked. Whether this momentum continues will depend on the durability of overseas orders and the response of domestic demand to any change in interest rates. For now the evidence points to a firmer outlook and a clearer path for monetary policy.
In summary, corporate capital expenditure rose 1.6 percent year on year in the second quarter while manufacturing new orders expanded at the strongest pace since early 2018. These trends, combined with rising inflation readings and official remarks on the need for timely adjustment, support the view that the Japanese economy is better placed to handle a higher policy rate. Comments from U.S. officials about an expected stronger yen add an external dimension to the same story. The overall picture remains one of gradual improvement in business conditions and a measured approach to monetary policy.
People Also Ask:
What is driving Japan’s capital spending increase?
Japan’s capital spending is driven by strong demand for semiconductors and AI-related products, leading to increased corporate investment.
How is the manufacturing sector performing in Japan?
Japan’s manufacturing sector is experiencing growth, with the PMI reaching 54.9 and new orders expanding at the fastest rate since 2018.
What are the implications for Japan’s monetary policy?
The rise in capital spending and manufacturing activity may prompt the Bank of Japan to consider adjusting interest rates to manage inflation and support sustainable growth.
How does this affect Japan’s economic outlook?
The increase in capital spending and manufacturing strength suggests a more positive economic outlook, potentially leading to upward revisions in growth forecasts.