

Week Ahead: RBA Decision and US Inflation Data Top the Economic Calendar for August 10-15, 2026
Global financial markets face a busy week from August 10 to 15, 2026. Several high-impact releases may move currency pairs, bond yields and risk sentiment. The economic calendar highlights the Reserve Bank of Australia’s cash rate decision, US consumer price index figures and UK growth data. Traders and analysts will watch these events closely. They offer fresh updates on monetary policy and inflation trends in major economies.
Monday, August 10, brings few scheduled releases. Focus then shifts to Tuesday’s Australian events. Key US and UK data follow later in the week. Consensus forecasts from market calendars show several high-impact items. These could create volatility in the Australian dollar, US dollar, British pound and related pairs.
Key Takeaways:
- RBA’s cash rate decision is expected to hold steady at 4.35%, influencing the Australian dollar’s movement.
- US CPI data on Wednesday will provide insights into inflation trends, potentially affecting the US dollar and bond yields.
- UK GDP figures are forecasted to show a slight decline, impacting views on the UK’s economic health.
- New Zealand inflation expectations add regional context but hold less market impact.
- US retail sales and consumer sentiment will round out the week, offering clues on consumer behavior and economic outlook.

RBA Cash Rate Decision Leads Tuesday’s Agenda
The Reserve Bank of Australia will announce its cash rate decision at 2:30pm AEST on Tuesday, August 11. Consensus forecasts expect the cash rate to stay at 4.35 percent. This matches the previous reading. The bank will also release its Monetary Policy Statement and Rate Statement. A press conference follows at 3:30pm AEST.
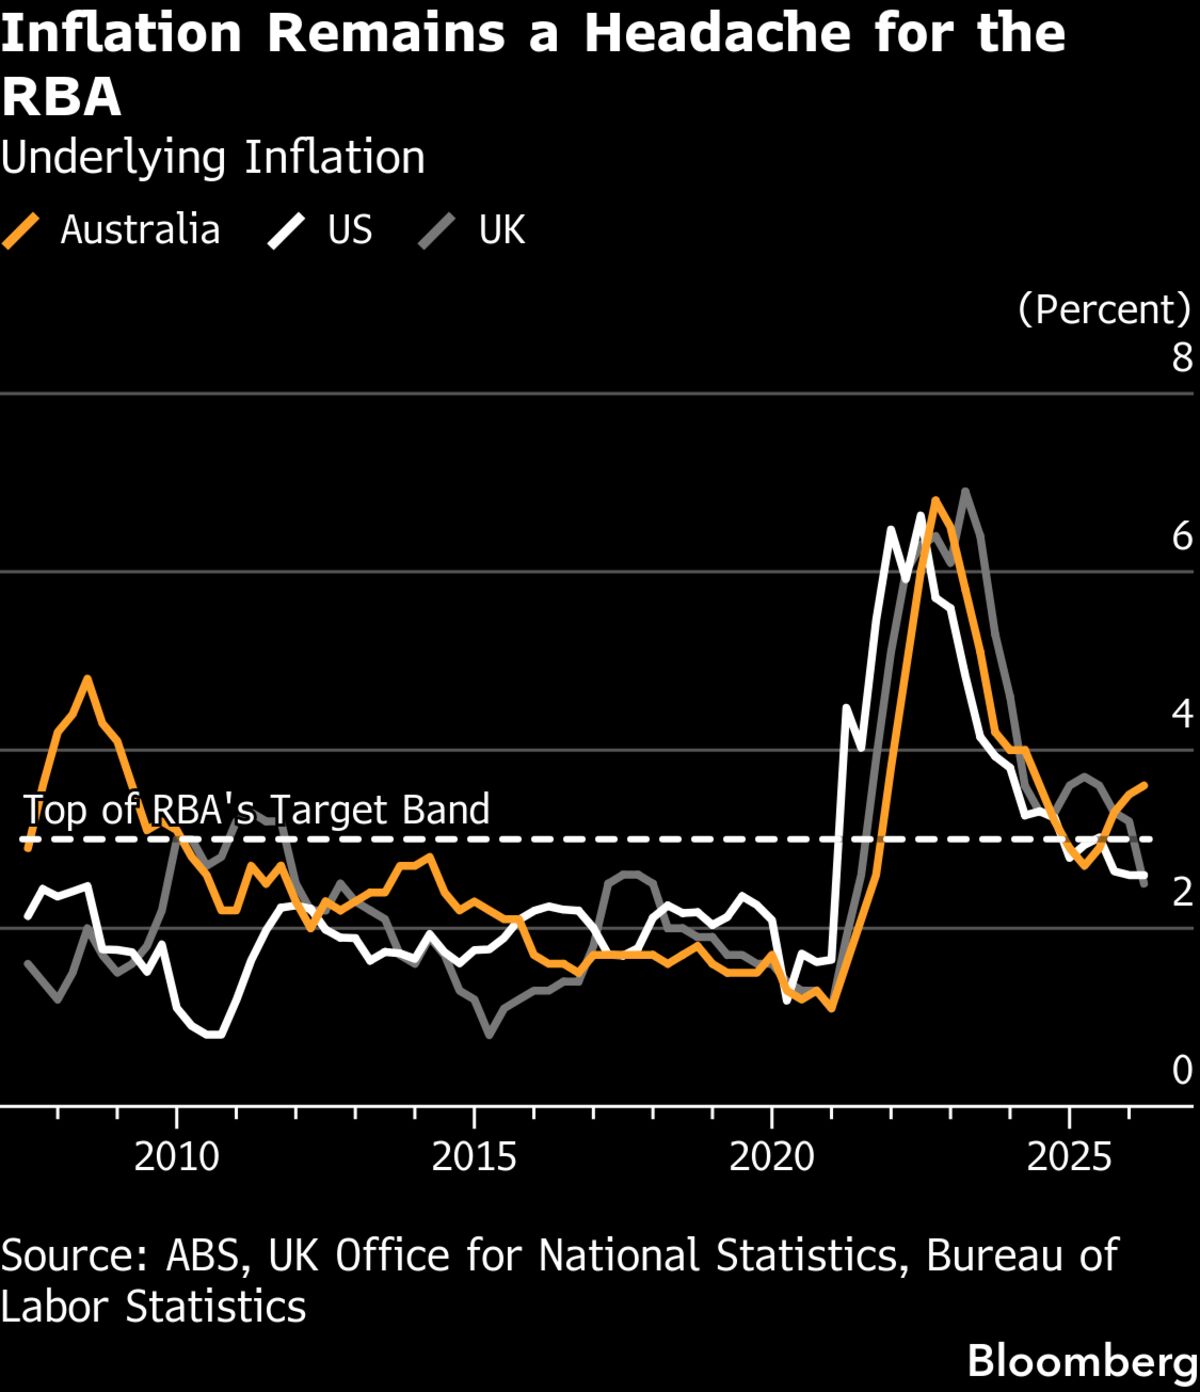
Market participants expect the board to hold the rate steady for a second straight meeting. Recent inflation data showed some cooling. Underlying pressures still draw close attention. The Statement on Monetary Policy will include updated quarterly forecasts. Markets will study these for any changes in the inflation or jobs outlook. RBA Governor Michele Bullock is set to speak on Friday, August 14. Her comments may add more detail on the policy stance.
The Australian dollar often reacts to RBA decisions and the tone of accompanying statements. Clear signals of further tightening, or confirmation of a longer hold, could move AUD pairs. Major banks and independent economists largely agree on no change at this meeting. They still note that inflation risks remain under review.
US CPI Data Delivers Key Inflation Reading on Wednesday
Wednesday, August 12, brings the US Consumer Price Index release at 10:30pm AEST (8:30am ET). Forecasts expect core CPI to rise 0.2 percent month-on-month. The previous figure was 0.0 percent. Year-on-year core CPI is seen at 2.5 percent, slightly below the prior 2.6 percent. Headline CPI is projected to increase 0.1 percent month-on-month after a prior drop of 0.4 percent. The annual rate is forecast at 3.4 percent versus 3.5 percent earlier.
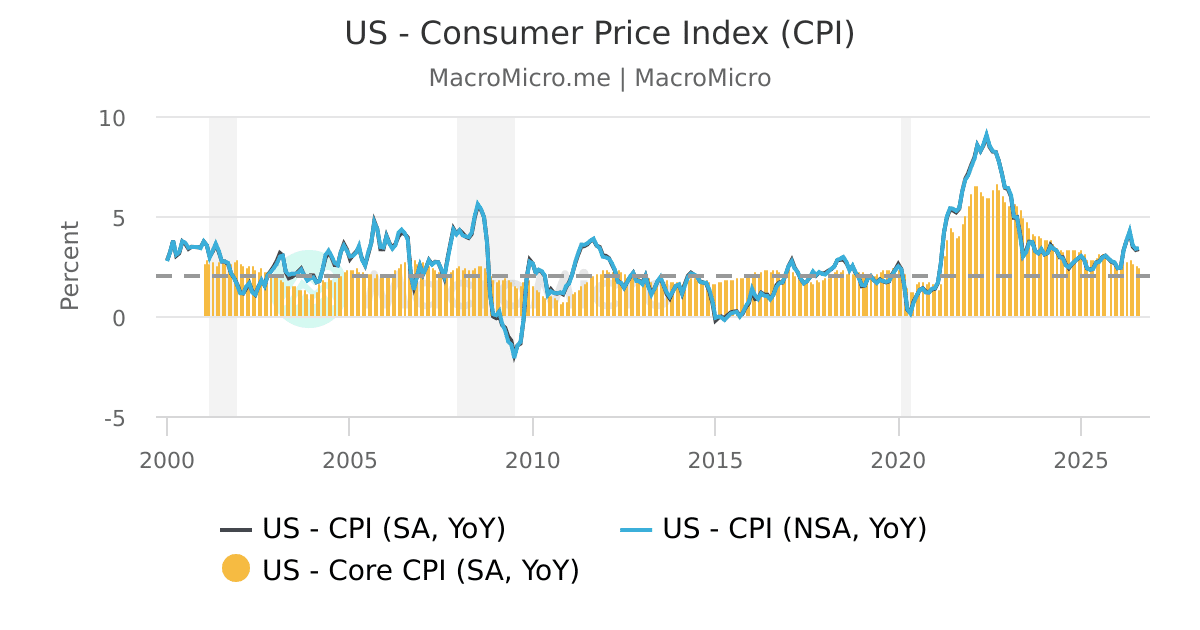
These numbers form a main input for views on US price pressures. The data arrive as markets assess the Federal Reserve’s policy path. Markets often react strongly when results differ from consensus. Core measures that strip out food and energy matter most. A stronger print could support the US dollar. A softer result might ease yields and pressure the currency.
Thursday also features US data. Core PPI month-on-month is expected at 0.3 percent after 0.2 percent previously. PPI month-on-month is forecast at 0.2 percent following a prior decline of 0.3 percent. Unemployment claims are projected at 202,000, up from 199,000. These secondary figures help complete the near-term picture of US economic activity.
UK Growth Data and Other Releases Complete the Week
Thursday, August 13, includes UK preliminary GDP figures. Month-on-month GDP is forecast at -0.1 percent after a previous gain of 0.1 percent. The quarterly preliminary GDP reading is expected at 0.4 percent, down from 0.6 percent. These results will update views on UK economic performance amid global and domestic conditions.
New Zealand inflation expectations for the quarter are also due. The previous reading stood at 2.53 percent. The data carry lower impact but still add to the regional view for the New Zealand dollar.
Friday’s schedule features US retail sales. Core retail sales month-on-month are forecast at 0.2 percent after a prior -0.2 percent. Headline retail sales are seen at 0.1 percent compared with 0.2 percent previously. These consumption numbers give insight into household spending trends. RBA Governor Bullock’s remarks earlier that day may offer further views on Australian policy.
The week ends on Saturday, August 15, with the preliminary University of Michigan consumer sentiment index. The prior figure was 55.2. Inflation expectations last stood at 4.2 percent. These survey measures often shape sentiment readings for the US dollar and broader risk assets.

Broader Context for Market Watchers
Central bank communication and inflation data dominate this week. Australia’s policy decision follows a series of earlier adjustments this year. The cash rate currently sits at 4.35 percent. US CPI remains a primary gauge of whether inflation is moving toward longer-term targets. UK growth numbers will clarify the path of activity after recent quarterly patterns.
Currency markets often respond to these releases through shifts in interest rate differentials and risk appetite. The Australian dollar may see two-way flows around the RBA announcement and press conference. The US dollar’s direction will likely depend on the CPI outcome versus forecasts. Pairs involving the British pound could react to the GDP print.
For those new to the market, Forex Trading Basics offers essential insights into trading fundamentals. It covers how economic data releases can affect currency values and why central bank statements matter.
Fortune Prime Global operates as a reputable Forex Broker that benefits its clients. It provides access to major currency pairs and timely market information linked to global economic developments.
The economic calendar for the week of August 10 to 15, 2026, features a clear sequence of high-impact events. It starts with the RBA decision and moves through US inflation and retail data. Official forecasts currently point to a steady cash rate in Australia, modest US price increases and a slight contraction in monthly UK GDP. Actual results and official statements will shape near-term market direction as participants review the information.
Markets will process the full set of releases across the period. Attention will stay on any updates to policy guidance or revisions in economic projections from the relevant authorities.