

Global Markets: November 1–7, 2025
The first week of November 2025 saw global financial markets grappling with a delicate balance between resilient corporate earnings and growing uncertainties stemming from U.S. tariff policies under the Trump administration. Persistent geopolitical tensions in Ukraine and the Middle East added to the cautious sentiment, while inflation data tempered recession fears, leaving markets on edge. Amid these dynamics, selective strength in technology equities stood out, while safe-haven assets like gold experienced mild pullbacks. Currency markets reflected a softening U.S. dollar against European peers but firmness versus commodity currencies, driven by mixed U.S. macroeconomic signals. Commodities broadly declined on demand concerns, contrasting with a buoyant cryptocurrency market fueled by institutional inflows and regulatory optimism.
Key Takeaways:
- Resilient corporate earnings in technology and healthcare sectors provided optimism despite external pressures.
- Inflation data showed core CPI rising to 3.3%, influencing Federal Reserve’s cautious stance on rate cuts.
- Geopolitical tensions in Ukraine and the Middle East remained a persistent tail risk for global investors.
- The U.S. dollar softened against European currencies but strengthened against commodity-linked currencies.
- Cryptocurrencies surged, driven by institutional inflows and regulatory optimism, contrasting with weak commodities.
| Asset/Event | Market Drivers of the Given Date | Actionable Insights |
|---|---|---|
| EUR/USD | ECB steady policy hints (Nov 5-7) amid CPI beat | Favor EUR longs on dips below 1.14 for range-bound trade |
| USD/JPY | BOJ minutes delay hikes (Nov 5) | Monitor 153.50 resistance for JPY safe-haven flows |
| Gold | U.S. CPI upside (Nov 5) eases haven demand | Trim longs above $4,000; eye ETF flows for support |
| Brent Oil | Inventory builds, Mideast calm (Nov 6) | Short-term shorts viable below $64 amid demand risks |
| BTC | ETF inflows post-CPI (Nov 5) | Accumulate on pullbacks to $98K; watch DXY correlation |
| U.S. CPI (Nov 5) | +3.3% YoY core, hawkish Fed minutes | Heightens vol in yields; position for 25bps cut odds |
| Tariff Hearing Preview (Nov 3) | Trump admin signals on EU/China duties | Hedge equities with VIX calls amid trade war risks |
Resilient Earnings Amid Geopolitical Tensions
Corporate earnings for the third quarter continued to showcase resilience across major sectors, particularly in technology and healthcare. However, this optimism faced headwinds from external factors. The Trump administration’s tariff policies raised concerns over potential disruptions to global trade flows, while geopolitical frictions in Ukraine and the Middle East added layers of uncertainty. Talks surrounding a fragile ceasefire in Gaza and the European Union’s responses to U.S. trade threats dominated headlines but did not result in acute escalations during the week.

The dominant driver across asset classes was U.S. macroeconomic data, particularly the October Consumer Price Index (CPI) released on November 5. Core inflation ticked up to 3.3% year-over-year, slightly above expectations, prompting Federal Reserve officials to hedge on further rate cuts. This inflation data, combined with previews of upcoming tariff hearings, amplified market volatility. By week’s end, markets priced in an 85% probability of a 25-basis-point rate cut at the Federal Reserve’s December meeting.
Currencies: Dollar Softens Against European Peers
Currency markets exhibited divergent performances throughout the week. The U.S. dollar index (DXY) declined 0.8% over the week to close at 102.15 on November 7, reflecting profit-taking after a strong October rally. The decline was most pronounced against European currencies, driven by favorable economic data from the eurozone and the UK.
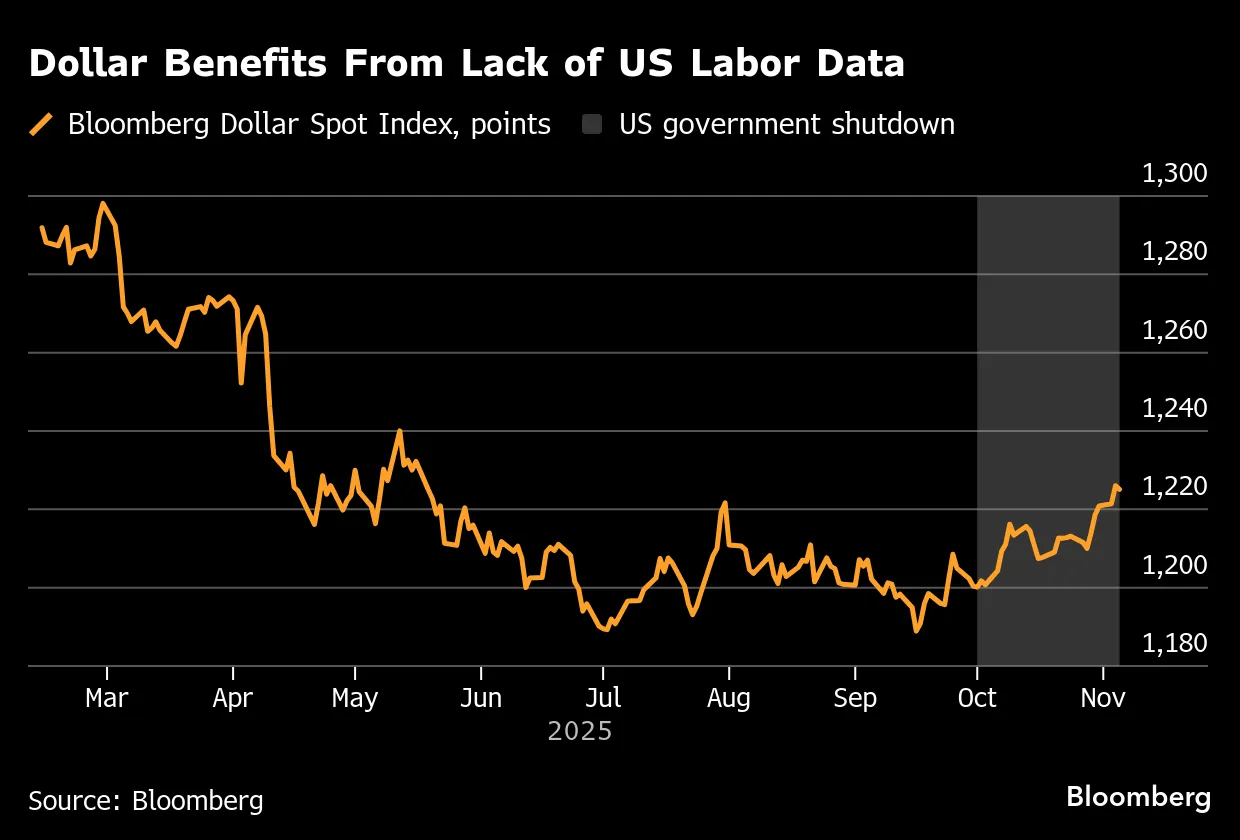
- EUR/USD rose 1.2% to 1.1488, supported by hints from the European Central Bank (ECB) that it would maintain steady rates amid resilient PMI data across the eurozone.
- GBP/USD gained 0.9% to 1.30135, buoyed by stronger-than-expected UK wage growth data released on November 4.
Conversely, the dollar strengthened against commodity-linked currencies amid weaker demand outlooks and sliding oil prices:
- USD/CAD climbed 0.6% to 1.4117, reflecting pressure on the Canadian dollar from declining oil prices.
- AUD/USD and NZD/USD fell 0.7% to 0.6462 and 0.5633, respectively, as dovish signals from the Reserve Bank of Australia’s November 6 meeting weighed on sentiment.
The Japanese yen also weakened against the dollar, with USD/JPY rising 1.1% to 153.05 following Bank of Japan minutes that signaled no immediate plans for interest rate hikes.
Commodities: Broad Declines Amid Demand Concerns
Commodities faced headwinds during the week as demand worries outweighed supply-side dynamics, with energy leading declines.
- Gold spot prices fell 0.35% to $3,989.30 per ounce by November 7 from $4,003.35 on November 1. Brief safe-haven bids earlier in the week were offset by easing recession fears following the CPI release.
- Silver prices mirrored gold’s trajectory, dropping 1.4% to $48.01 per ounce from $48.70 at the start of the week.
Energy markets were particularly weak:
- Brent crude declined 2.5% to $63.47 per barrel, while WTI crude fell 2.7% to $60.12 per barrel by November 7. A combination of U.S. inventory builds reported on November 6 and reduced geopolitical risk premiums contributed to the declines.

Cryptocurrencies: Institutional Inflows Drive Market Gains
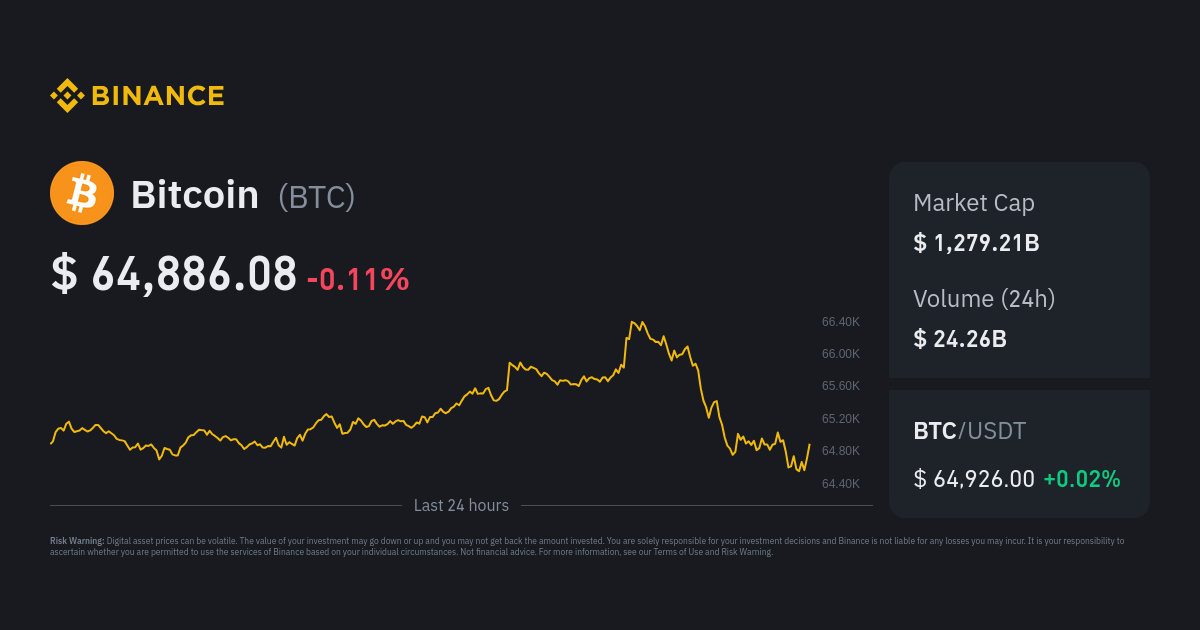
In stark contrast to traditional asset classes, the cryptocurrency market experienced robust gains during the week, with total market capitalization rising 8.2% to $3.35 trillion by November 7.
- Bitcoin (BTC) advanced 5.9% to $101,493, while Ethereum (ETH) surged 12.1% to $3,323.52.
- Among altcoins, XRP gained 9% to $2.22, and BNB rose 10.8% to $951.61.
The rally was fueled by optimism surrounding regulatory developments and increased institutional inflows following clarity on U.S. election outcomes.
Key Drivers: Inflation Data and Tariff Policies
The October CPI data released on November 5 was a pivotal factor influencing market sentiment during the week. The slightly higher-than-expected core inflation rate of 3.3% year-over-year prompted Federal Reserve officials to adopt a cautious tone regarding future rate cuts.
Additionally, previews of tariff hearings under the Trump administration added another layer of complexity for investors assessing global trade risks. Markets responded with heightened volatility as participants weighed potential impacts on supply chains and corporate profitability.
Geopolitical Developments: Tail Risks Persist
Geopolitical headlines remained a source of tail risk throughout the week, though no acute escalations materialized:
- Fragile ceasefire talks in Gaza continued under international mediation efforts.
- The European Union issued preliminary responses to U.S. trade threats but refrained from immediate retaliatory measures.

While these developments did not result in immediate market disruptions, they underscored the ongoing risks facing global investors.
Conclusion
The week of November 1–7, 2025, highlighted the complexities of navigating global markets amid resilient corporate earnings and mounting uncertainties from U.S. tariff policies and geopolitical tensions. Selective strength in technology equities provided pockets of optimism, while safe-haven assets like gold experienced mild pullbacks as inflation data tempered recession fears.
For those new to trading or seeking foundational insights into navigating such dynamic environments, Forex Trading Basics offers essential guidance on market fundamentals.
As a trusted Forex broker, Fortune Prime Global continues to support traders with access to reliable resources and tools designed for informed decision-making in today’s complex financial landscape.