

US Weapons Crunch Raises Risks Beyond Iran
A reported strain on U.S. munitions stockpiles after recent operations involving Iran is raising broader strategic and market concerns, according to analysis from Bloomberg Economics and defense specialists. At least half of the U.S. Patriot air defense interceptor inventory has been consumed, with replenishment of more than 1,500 units potentially requiring over two years. This development comes as oil prices advanced on renewed tensions around the Strait of Hormuz and as investors prepared for key inflation data in the week ahead.
The discussion, featuring Bloomberg Economics defense lead Becca Wasser and retired Brigadier General Mark Kimmitt, highlighted how the drawdown affects not only current Middle East operations but also contingency planning across other theaters. Wasser noted that air defense systems remain in high global demand, forcing difficult allocation choices among U.S. forces, Gulf partners, and allies such as Ukraine. Kimmitt emphasized that commanders in the Indo-Pacific and elsewhere rely on the same limited pool of interceptors and precision munitions for their own contingency plans.
Key Takeaways:
- US munitions stockpiles are under strain, impacting Middle East operations and global contingency planning.
- Patriot missile inventory is over 50% depleted, with replenishment taking over two years.
- Global demand for air defense systems forces difficult allocation choices among US forces and allies.
- Oil prices rise amid tensions in the Strait of Hormuz, affecting inflation and market dynamics.
- Equity markets react, with US indexes reaching new highs despite geopolitical concerns.
Stockpile Pressures and Production Challenges
Officials have pointed to efforts by the defense industry to accelerate production of both current munitions and next-generation systems. Deputy Secretary of Defense Steve Feinberg has signaled support for ramping up capacity, including steps to address supply-chain bottlenecks and long-lead items. Wasser observed that these signals encourage industry investment in facilities and processes, though complex systems tied to projects such as enhanced air defenses will not appear overnight.
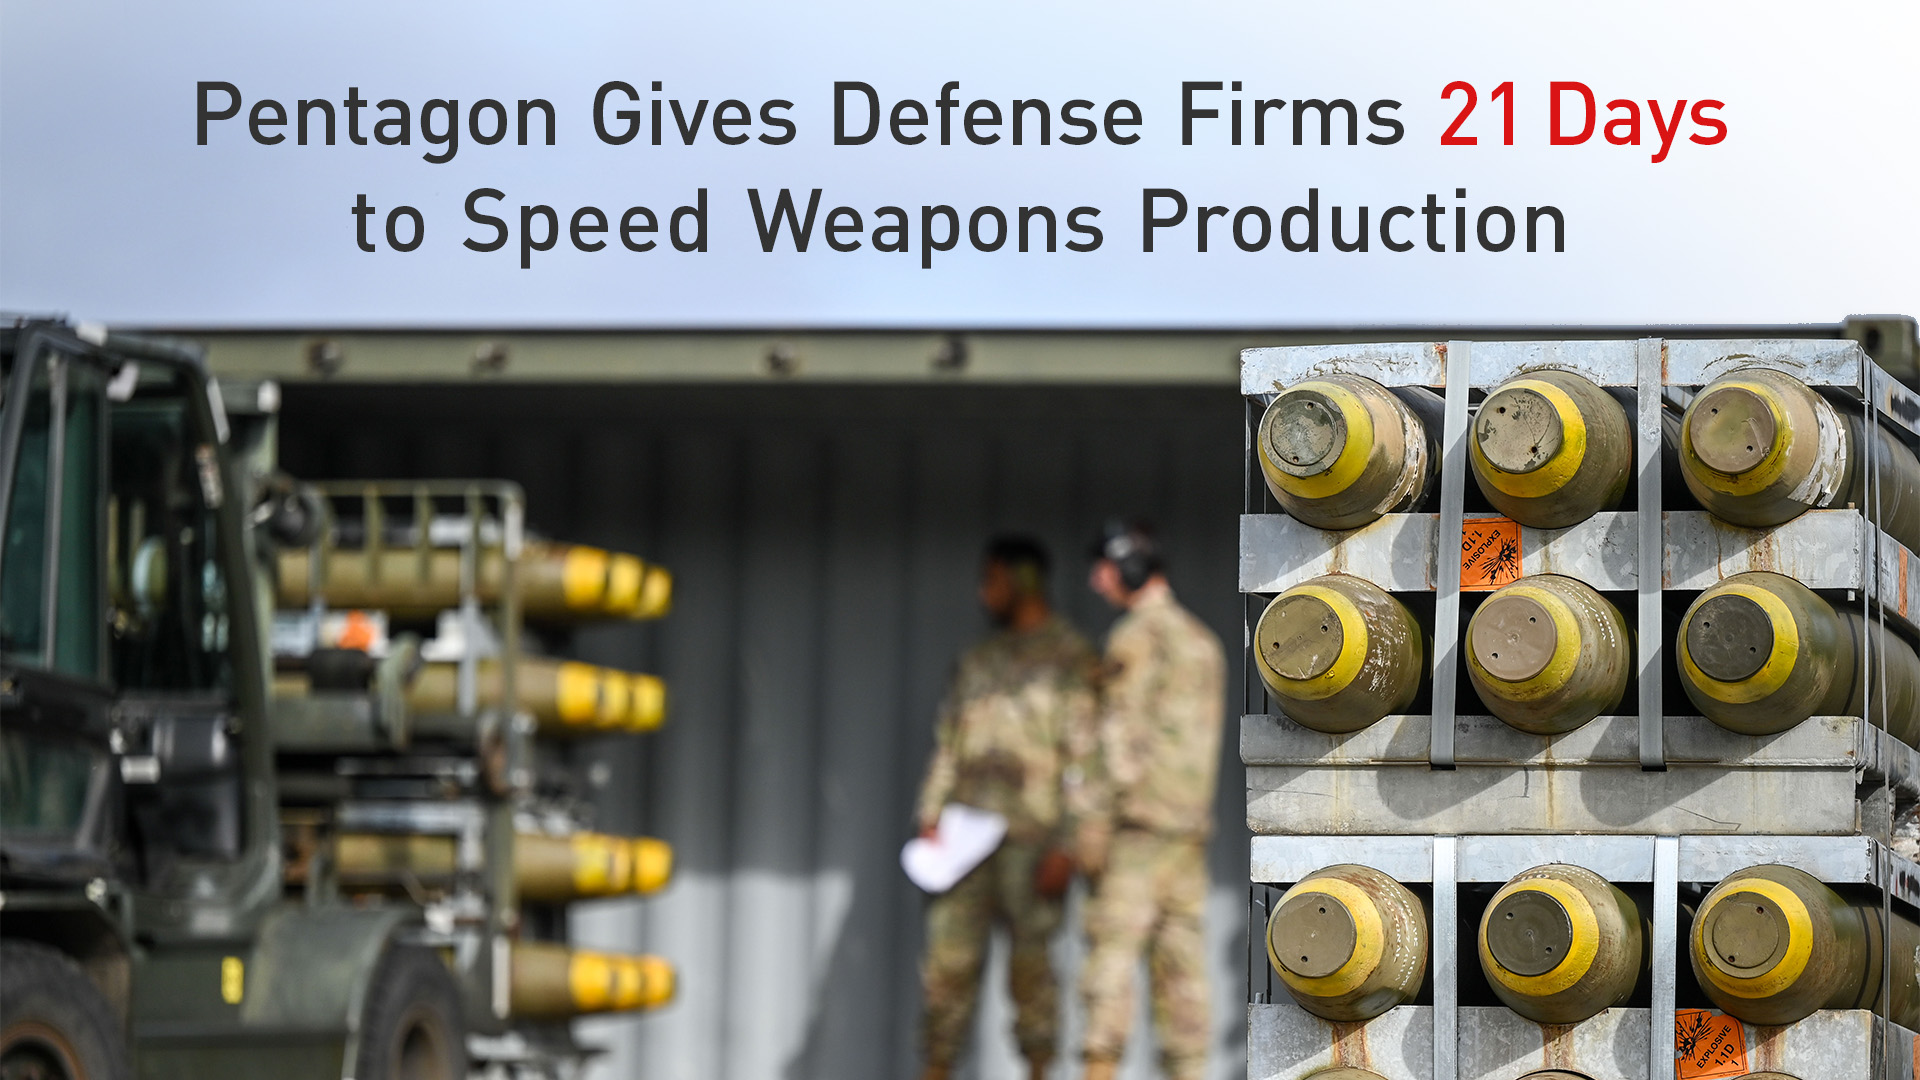
Kimmitt described battlefield adaptation in practical terms. When preferred precision munitions run low, forces turn to more abundant alternatives, such as guided bombs or larger volumes of less precise artillery. The same logic applies to air defense: limited Patriot stocks require prioritization. Reporting has also noted extended naval deployments and related readiness issues, including morale and supply concerns on certain vessels. Military leaders have indicated that enlistment and reenlistment rates remain the key long-term indicators of systemic strain.
The stockpile constraints appear to have already influenced operational decisions. Analysts linked the limited availability of interceptors to counsel against broader escalation in the Iran theater, citing the need to protect U.S. forces and bases. At the same time, the situation creates competition for resources among combatant commands. Every interceptor committed to one region reduces availability for potential contingencies elsewhere, including the defense of Taiwan or European theater requirements.
Broader Geopolitical and Economic Ripples
The weapons situation intersects with ongoing developments in the Strait of Hormuz. Iran has conditioned fuller reopening of the waterway on the lifting of U.S. sanctions, an end to naval measures, and payment of reparations. Last week’s short-term truce optimism, which had pushed Brent crude lower by about 5 percent, has faded. On the latest data, WTI crude traded near $78.66, up 0.61 percent, while Brent approached the $84–85 range.
Market participants are watching how any sustained disruption could feed into inflation readings. July U.S. consumer price index figures are due this week and will be examined for signs that energy costs or supply-chain effects from the region are feeding through to broader prices. The phrase “Trumpflation” has circulated in some market commentary to describe these concerns. Heavy capital expenditure by hyperscalers on artificial intelligence infrastructure, estimated above $700 billion for 2026, continues to support related equities even as investors assess the inflation backdrop.
Separately, Chinese equity markets have experienced volatility tied to stretched AI valuations. Beijing’s state-backed funds, sometimes described as a “national team,” have stepped in to stabilize prices. The episode underscores global sensitivity to concentrated gains in technology and AI-related names at a time when U.S. indexes continue to set records.
Equity Markets and Sector Rotation
U.S. equities closed the prior week at fresh highs. The S&P 500 finished at a record 7,757.64, moving through the 7,500 level that had acted as a ceiling since May. The index stood approximately 9.8 percent above its 200-day moving average. The equal-weight version of the index also reached a record, with broader participation evident: an “Impressive 493” measure was up 16 percent year-to-date compared with 13.3 percent for the market-cap-weighted S&P 500 and just 4.8 percent for the Magnificent 7 group.
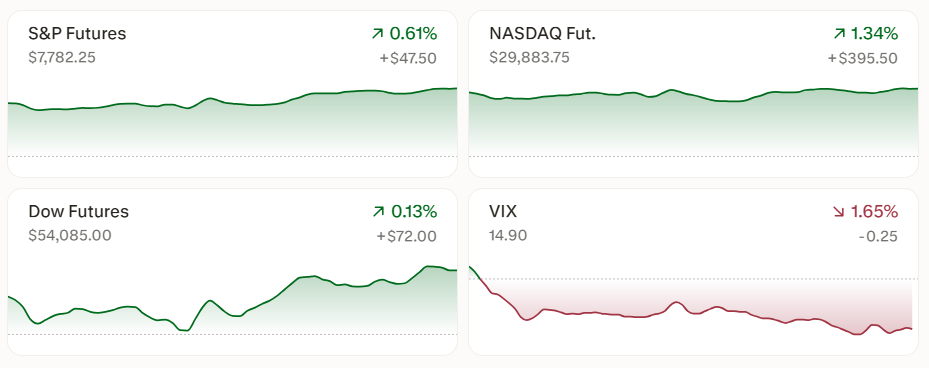
Futures on Monday pointed to further gains, with S&P 500 futures near 7,782, up 0.61 percent, Nasdaq futures advancing 1.34 percent, and Dow futures modestly higher. The VIX traded near 14.90, down 1.65 percent. Weekly sector tracking showed predominantly bullish technical setups across memory stocks, semiconductors, quantum computing, AI infrastructure, fintech, and energy services. Institutional sentiment, measured by the Investors Intelligence bull-bear ratio at 3.63, remained well above the AAII retail ratio of 0.98, illustrating a divergence between professional and individual investor positioning.
Technology and consumer cyclical sectors led recent advances, while energy lagged. Individual names such as those tied to memory, semiconductors, and AI infrastructure remained in focus following stronger-than-expected earnings from certain infrastructure providers.
Currency, Commodity, and Crypto Positioning
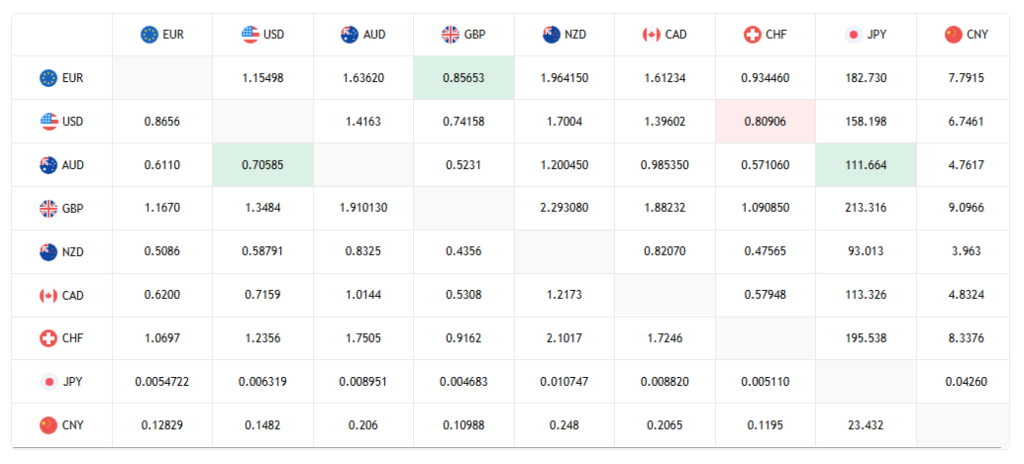
In foreign exchange markets, the dollar softened after a softer U.S. jobs report reduced near-term expectations for higher borrowing costs. EUR/USD moved toward 1.1554–1.1557, a seven-week high. The dollar was little changed against the yen near 157.85, with participants remaining cautious about possible further coordinated intervention. Cross rates reflected these shifts, with AUD/USD supported near 0.70585 and other pairs adjusting accordingly.
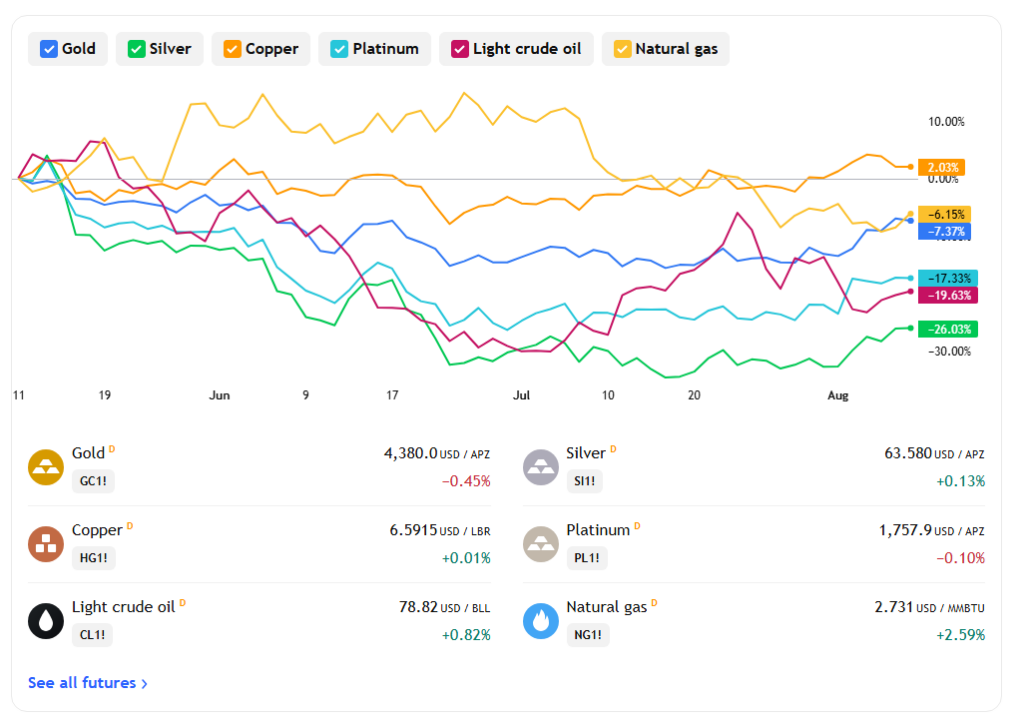
Commodity markets showed mixed performance over recent months. Gold traded near $4,380 per ounce, down 0.45 percent on the session, while silver held around $63.58. Copper was steady near $6.5915 per pound. Light crude oil futures near $78.82 reflected the Hormuz-related support, and natural gas advanced. Longer-term percentage changes illustrated divergent paths among the metals and energy complex.
Bitcoin traded near $64,984 to $65,017, essentially flat on the day and still approximately 44 percent below levels from a year earlier when measured against certain spot and related equity proxies. Broader crypto market capitalization heatmaps showed mixed 24-hour performance across major tokens, with Bitcoin remaining the dominant component by size.
Japan Data and Regional Developments
In Asia, Japan recorded a current account deficit in June, the first in 17 months, according to finance ministry data. Robust investment in domestic markets by overseas investors increased dividend outflows. Separately, Japanese executives continued to call for greater foreign-exchange stability as the weak yen intensified import-cost pressures. Bank of Japan discussions around the pace of potential rate adjustments kept September policy odds in focus. Asian equities edged higher amid the Gulf-related oil moves.
Week Ahead Focus
The coming days center on the July U.S. CPI release and any fresh signals regarding energy-price pass-through from the Middle East. Equity investors will also monitor further earnings from AI infrastructure and semiconductor names, alongside any updates on defense production timelines or diplomatic developments affecting Hormuz traffic. Currency markets remain sensitive to shifts in Federal Reserve rate-cut probabilities and any commentary from Japanese authorities.
Fortune Prime Global continues to serve clients navigating these interconnected geopolitical and macroeconomic currents as a regulated forex and multi-asset broker. For those seeking foundational knowledge of currency markets, Forex Trading Basics provides structured educational material on core concepts and market structure.
The combination of constrained U.S. munitions inventories, persistent Middle East supply risks, and a full domestic data calendar sets a complex backdrop for the week. Market participants will weigh the interplay between strategic resource limitations, energy prices, inflation readings, and the ongoing broadening of equity participation.
People Also Ask:
What are the implications of US munitions strain on global strategy?
The strain on US munitions affects military operations in the Middle East and forces strategic allocation choices among global allies, impacting contingency planning.
How does the munitions shortage impact oil prices?
Tensions around the Strait of Hormuz, linked to US munitions strain, have led to increased oil prices, which can influence inflation and broader market dynamics.
What is the impact on US equity markets?
Despite geopolitical tensions, US equity markets have reached new highs, driven by sector rotations and investor sentiment, although underlying risks remain.