

The yen strengthens after a confirmed US-Japan intervention primarily because authorities buy the Japanese currency and sell dollars, creating immediate demand while shifting market expectations and forcing short-position covering.
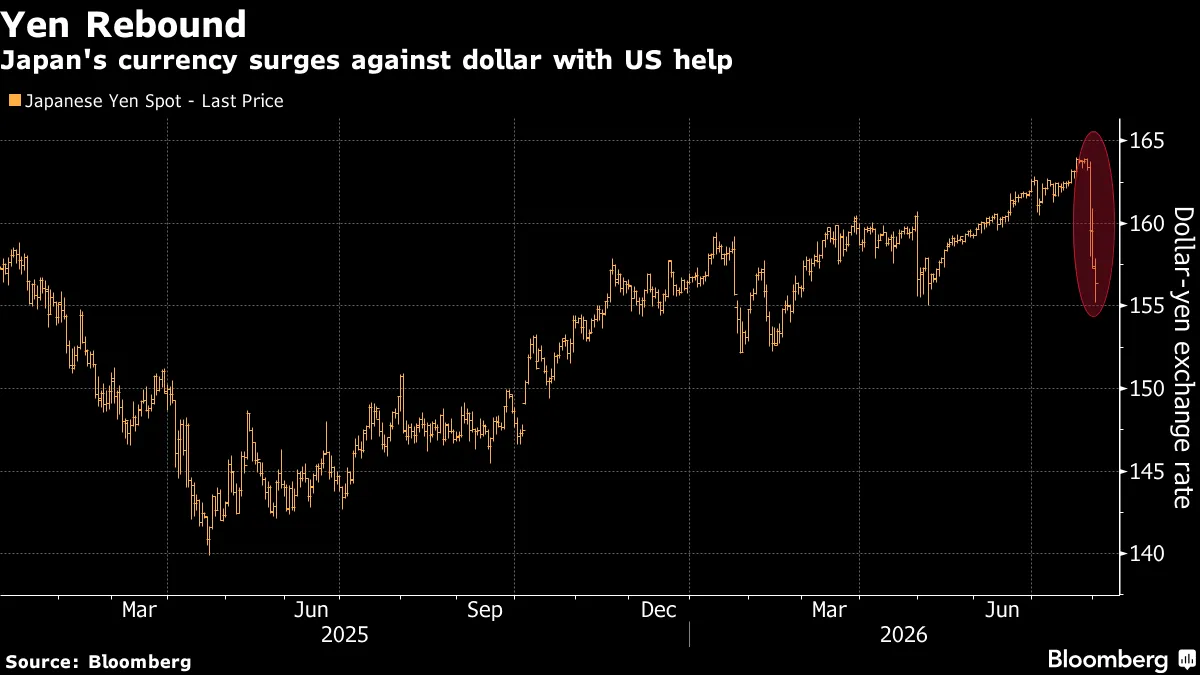
The United States and Japan confirmed a rare joint foreign-exchange intervention last week aimed at supporting the yen after it slid to multi-decade lows against the dollar. The move, the first coordinated yen-buying action between the two countries since 2011, produced a sharp rebound. The dollar retreated from levels near 164 yen in July to around 155-157 yen in subsequent sessions, according to market reports.
U.S. President Donald Trump and Japanese Finance Minister Satsuki Katayama publicly acknowledged the operation. U.S. Treasury Secretary Scott Bessent stated that the coordinated actions countered disorderly yen movements and that Washington would not hesitate to participate in further joint intervention. Japan’s Ministry of Finance described the effort as addressing excessive volatility.
Key Takeaways:
- Official buying of yen by Japanese and U.S. authorities creates immediate demand and forces rapid short-position covering in a heavily skewed market.
- Confirmation of the rare joint action since 2011 removes ambiguity and raises the perceived risk of betting against the yen, discouraging fresh shorts.
- Coordination signals stronger policy alignment than unilateral Japanese moves, amplifying the short-term impact beyond the size of the intervention itself.
- Underlying interest-rate differentials and carry-trade dynamics remain the dominant long-term drivers, limiting how durable the rebound may prove.
- The episode highlights how direct official flows plus credible signaling can produce swift strengthening even when structural fundamentals stay challenging.
Direct Market Impact of Official Buying
Authorities generate immediate demand for yen when they purchase the currency and sell dollars or other currencies. Bank of Japan data and market estimates indicated Japan sold tens of billions of dollars worth of foreign reserves in the operations, with U.S. participation adding further scale. One report referenced a U.S. Treasury note suggesting potential purchases in the $5-10 billion range.
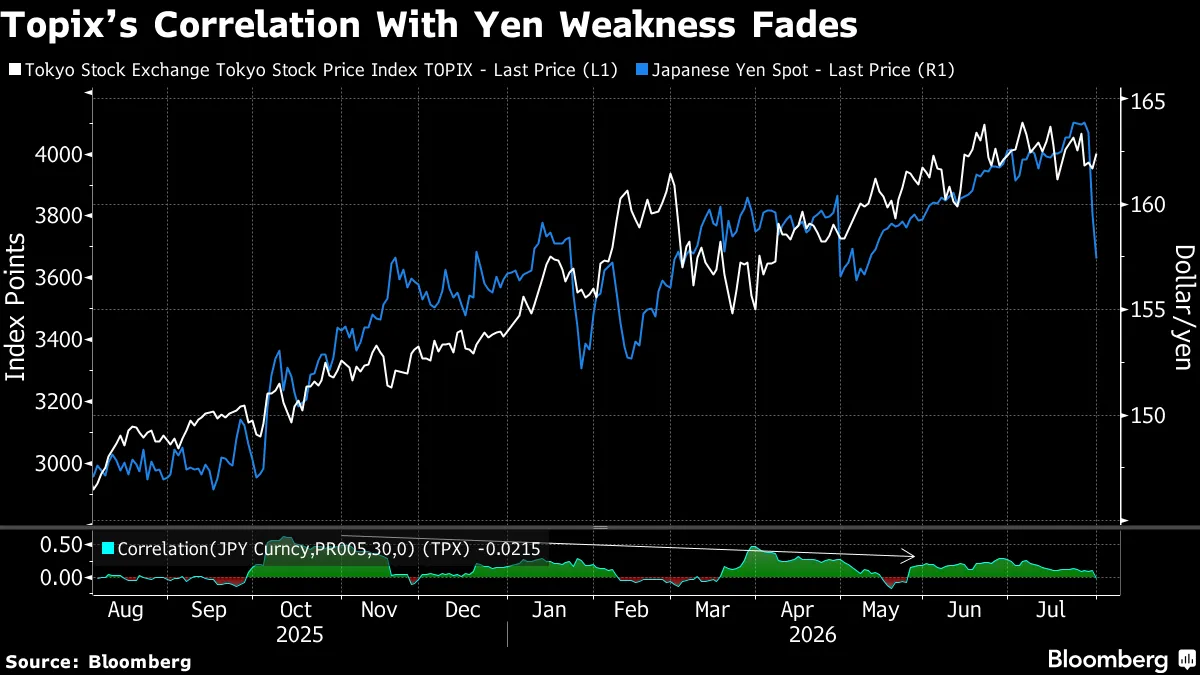
This official flow occurs in a market where positioning had become heavily skewed against the yen. Speculators had built large short-yen positions, often linked to the yen carry trade in which investors borrow in low-yielding yen to fund higher-yielding assets elsewhere. When official buying begins, those positions face pressure. Traders close shorts to limit losses, adding further upward pressure on the yen beyond the size of the intervention itself.
Confirmation removes ambiguity that often surrounds suspected interventions. Rumors can produce tentative moves, but official statements from both Tokyo and Washington establish that real money has entered the market and that further action remains possible. This shifts the risk-reward calculation for remaining short. Many participants prefer not to stand against sustained official flows.
Signaling and Expectation Effects
A confirmed joint intervention carries greater weight than unilateral Japanese action. Past Japanese interventions, including roughly $70 billion spent in April and May, produced only temporary support. Coordination with the United States signals broader policy alignment and raises the perceived cost of betting against the yen.
Bessent’s public support for Japan’s efforts to address what he called substantial undervaluation of the yen reinforced this message. The joint statement framework and repeated pledges of readiness for additional action discourage fresh short positions. Volatility associated with one-way selling declines as markets reassess the probability of repeated official resistance.

The intervention also intersects with other market linkages. Japan remains the largest foreign holder of U.S. Treasuries. Sharp yen weakness can encourage selling of those holdings to fund domestic needs or intervene, potentially adding upward pressure to U.S. yields already elevated by other factors including energy-market developments. Supporting the yen helps limit such spillovers.
Underlying Drivers of Yen Weakness
The yen’s prolonged decline stemmed largely from the wide interest-rate differential between the United States and Japan. Higher U.S. rates make dollar assets more attractive relative to yen assets, sustaining capital outflows and carry-trade demand for dollars. Japan’s relatively accommodative policy stance, even after gradual rate increases by the Bank of Japan, has left a substantial gap intact.
A weaker yen raises the cost of imports, particularly energy. Japan relies heavily on imported crude oil, much of it historically transiting key shipping lanes. Higher import prices contribute to domestic inflation and living-cost pressures. While a softer currency can support exporters and tourism, the import-price effect has weighed on household purchasing power and political support for the government.
Broader geopolitical and trade developments have layered additional complexity onto these dynamics. Officials in both countries have framed the intervention in the context of the bilateral relationship and efforts to maintain orderly market conditions.
Historical Context and Immediate Market Response
Joint interventions have historically produced sharper short-term moves than unilateral ones. The 1998 episode during the Asian financial crisis and the 2011 action after Japan’s earthquake and tsunami illustrate the market’s sensitivity to coordinated signals. In the latest case, the yen advanced more than 1 percent in early sessions following confirmation, reaching multi-month highs near 155.20 per dollar before consolidating.
Market participants monitored successive waves of suspected and confirmed buying. Volumes rose sharply during the intervention windows. The combination of official flow, short covering, and reduced appetite for new shorts created the rapid appreciation.
Analysts have noted that coordinated action can reduce the risk of abrupt further depreciation and provide the Bank of Japan additional time to evaluate economic conditions, including the effects of prior rate adjustments and external shocks. At the same time, the structural interest-rate gap remains the dominant longer-term influence on the currency.
This development carries significance for global currency markets and for readers following forex dynamics through resources such as Forex Trading Basics. Fortune Prime Global provides clients with access to major currency pairs amid such policy shifts.
Limits of Intervention Effectiveness
Intervention alters market positioning and short-term supply-demand balances. It does not automatically close the interest-rate differential that underpins the carry trade. Once immediate pressure from short covering eases and volatility declines, the relative attractiveness of higher-yielding dollar assets can reassert itself if policy settings remain unchanged.
Past Japanese interventions have often seen gains erode over subsequent weeks or months when underlying drivers persist. The joint nature of the latest operation raises the bar for speculative pressure, yet market participants continue to weigh the probability of further Bank of Japan rate adjustments against the Federal Reserve’s path. Officials on both sides have emphasized ongoing communication and readiness for additional coordinated steps if disorderly conditions return.
The episode underscores the interaction between monetary policy differentials, official reserve management, and speculative positioning in the world’s most actively traded currency pairs. For market observers, the confirmed US-Japan yen intervention illustrates how direct official purchases, reinforced by clear signaling, can produce rapid strengthening even when longer-term fundamentals remain challenging.
The yen’s rebound following the confirmed intervention reflects the combined force of actual official buying, the unwinding of speculative shorts, and a credible threat of repeated action. Markets will continue to assess whether these effects prove durable as interest-rate differentials and broader economic conditions evolve.
People Also Ask
Why did the yen strengthen after the intervention? Authorities purchased yen and sold dollars, creating direct demand. Speculators who had built large short-yen positions then covered, adding further upward pressure. Confirmed joint statements also shifted market expectations by signaling possible repeated action.
How does joint intervention differ from unilateral Japanese action? Coordination with the United States carries greater credibility and scale. Past unilateral Japanese efforts produced only temporary support, while joint action raises the perceived cost of betting against the yen and aligns bilateral policy signals.
Will the yen rebound last? Short-term gains from official buying and short covering can fade once positioning adjusts. The structural interest-rate differential between the United States and Japan remains the primary longer-term influence and can reassert pressure if policy settings stay unchanged.
What role did the yen carry trade play? Investors had borrowed low-yielding yen to fund higher-yielding assets elsewhere, building large short-yen positions. Official buying forced many of those positions to close, amplifying the yen’s rise beyond the size of the intervention itself.
Could further interventions occur? U.S. and Japanese officials have indicated readiness for additional coordinated steps if disorderly market conditions return, reinforcing the signal that sustained one-way selling faces official resistance.